Create a free account to get started

Unlock full course notes by signing up

  • Video lessons taught by top educators
  • Practice questions with guided solutions
  • Written review notes for reference
  • Expert answers anytime from course tutors

T-Accounts

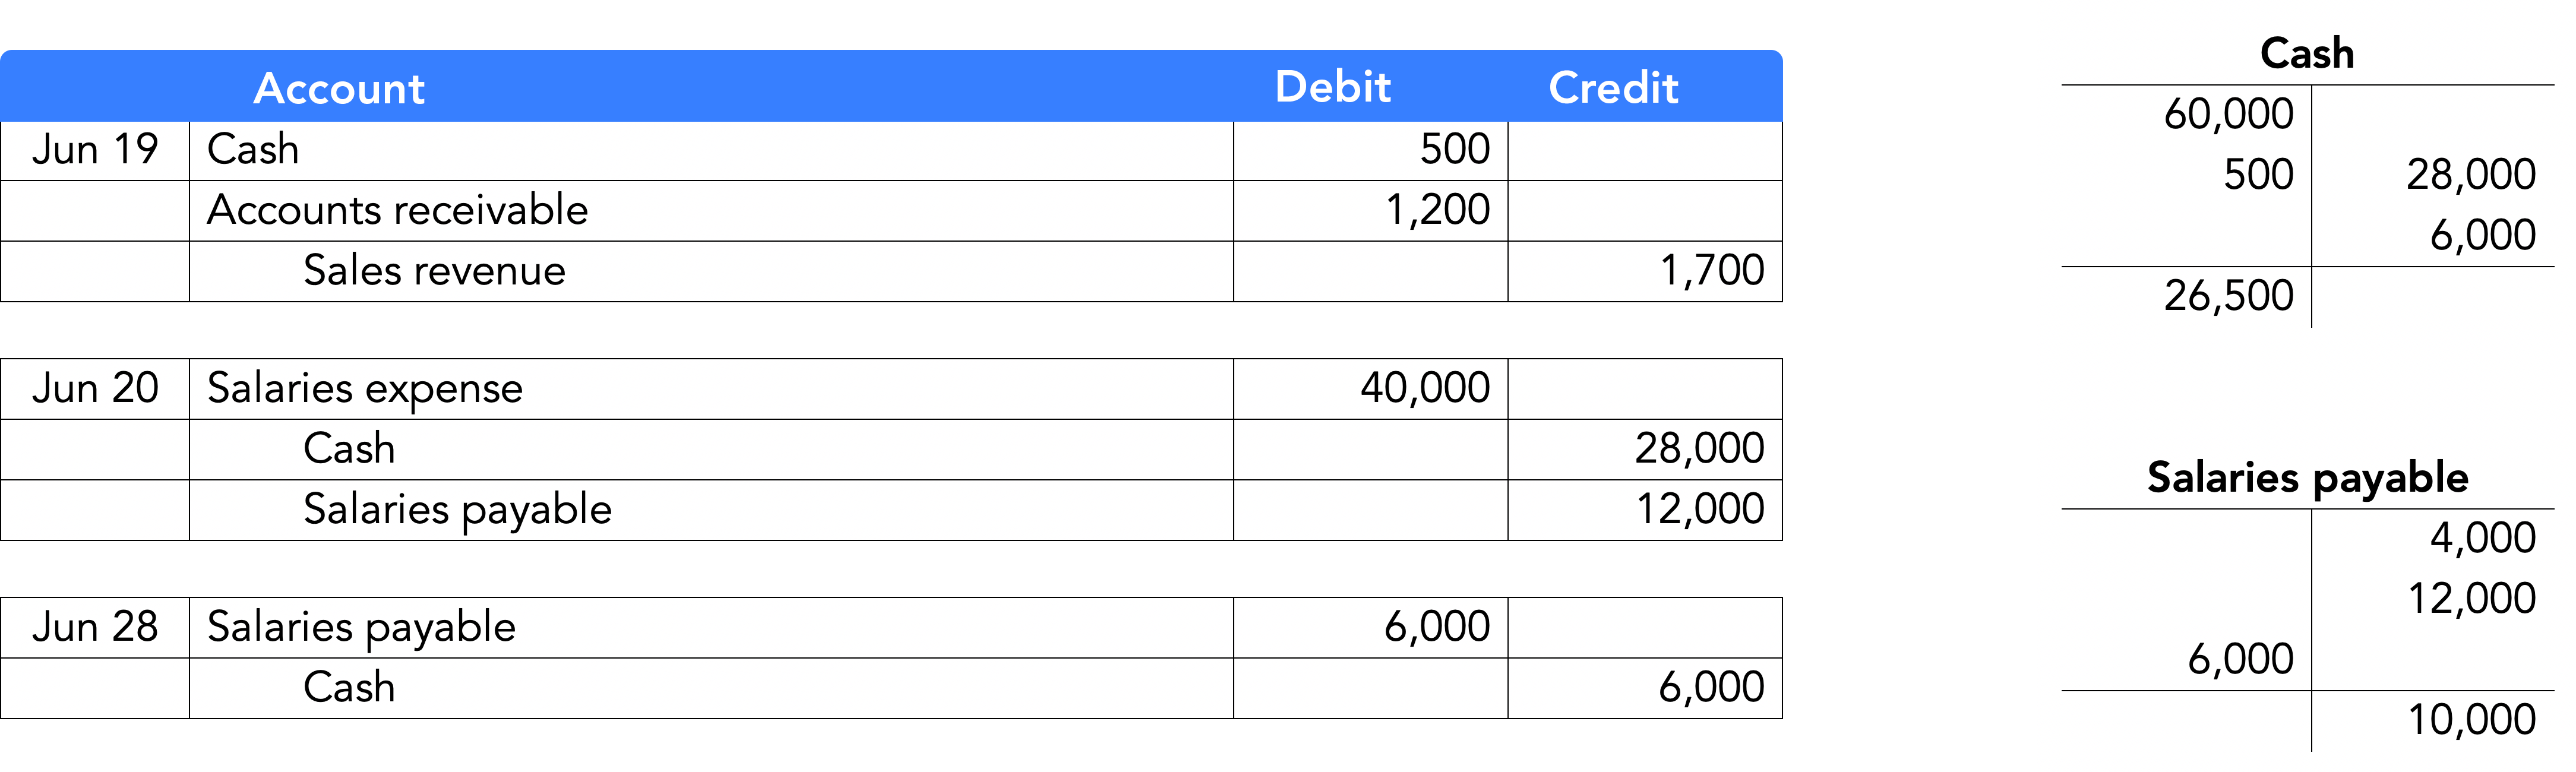
A T-account is a very useful tool used in accounting to keep track of all the transactions that affected a certain account type. We use t-accounts to balance accounts, determine what the balance of an account is in order to prepare financial statements and a variety of other reasons.
Image illustrating T-Accounts


Characteristics of a T-Account

  • Left side: debit; Right side: credit
  • Normal beginning and ending balances should be placed on the "natural" side of the account.
  • Debit for: assets and expenses
  • Credit for: liabilities, shareholders' equity and revenues
  • When a journal entry is written, the amounts in the entry are also placed in the T-accounts.


Image illustrating T-Accounts


Image illustrating T-Accounts


Create a free account to get started

Unlock full course notes by signing up

  • Video lessons taught by top educators
  • Practice questions with guided solutions
  • Written review notes for reference
  • Expert answers anytime from course tutors

Example: T-Accounts

Use T-Accounts to find the balances on January 31 of the following accounts: Cash, Accounts payable, Inventory and Sales revenue.
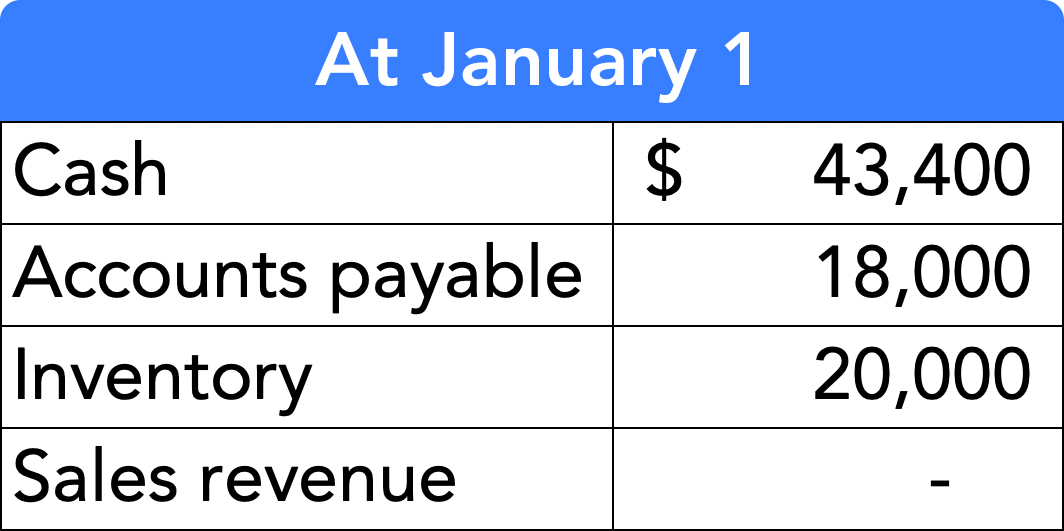

Image illustrating Example


Assume these are the only transactions that took place in January


Image illustrating Example


Practice: T-Accounts

Determine the balance of each account April 12th.


Illustration for practice question: Practice: T-Accounts


Illustration for practice question: Practice: T-Accounts


Your answers

Create a free account to get started

Unlock full course notes by signing up

  • Video lessons taught by top educators
  • Practice questions with guided solutions
  • Written review notes for reference
  • Expert answers anytime from course tutors

Practice: T-Accounts

Use T-accounts to solve each of the following independent situations.

A physical count of inventory on hand on December 31, 2020 indicates that the company has $38,000 worth of merchandise in stock. During the year, $50,000 of inventory was purchased in addition to another purchase. Management has misplaced the invoice for the second purchase and has therefore not recorded it. Looking at last year's balance sheet, the company ended 2019 with $84,000 of inventory, and it is known that during 2020 a total of $110,000 of inventory was sold. What is the value of the missing purchase?

Create a free account to get started

Unlock full course notes by signing up

  • Video lessons taught by top educators
  • Practice questions with guided solutions
  • Written review notes for reference
  • Expert answers anytime from course tutors