
Bank Reconciliation
At the end of each month, companies must reconcile their bank statement balance with the cash balance in the general ledger to determine the correct amount of cash that should be reported. This is necessary because certain items appear on the bank statement but not in the ledger, and others appear in the ledger but not on the bank statement.
Bank Statement Balance
- Cash balance according to bank's records
- Sent periodically to the company
- Only reflects transactions that have been recorded by the bank
Book Balance
- Cash balance according to company's bookkeeping
- Only reflects transactions that have been recorded in the company's general ledger

Deposits in Transit
- Also called outstanding deposits
- Cash or cheques received but not yet deposited
- Cash of cheques deposited after statement is printed
- Increases bank statement balance
Outstanding Cheques
- Cheques written but not yet taken from bank account
- Decreases bank statement balance
Bank Errors
- Over or understatement of deposits or withdrawals
- Could increase or decrease bank statement balance depending on error
- Example: Bank incorrectly debited a $400 cheque as $4,000.
Deposits by Bank
- Any deposit of cash into account by the bank
- Increases book balance
- Example: wire transfers, collections of notes by the bank, interest on account balance
Bank Service Charges
- Expense charged by the bank for services
- Decreases book balance
Non-Sufficient Funds Check (NSF)
- Check deposited and rejected by the bank
- Check issuer did not have enough money in their account
- Decreases book balance
Book Errors
- Bookkeeping errors affecting cash
- Could increase or decrease book balance depending on error.
- Example: Incorrectly recording a cash sale as $750 instead of $570.
Bank Reconciliation Statement

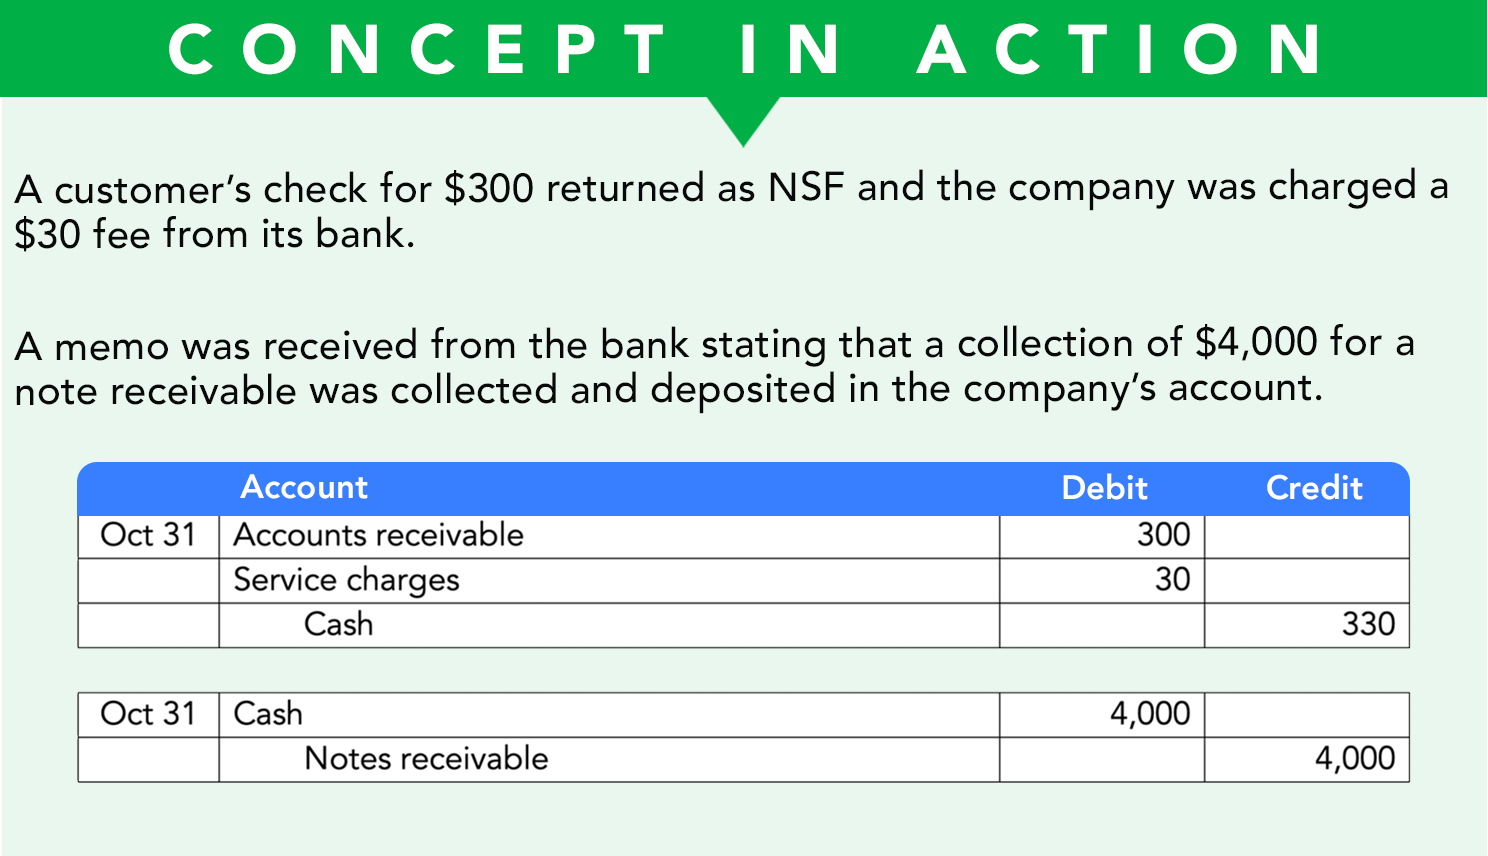
Bank Reconciliation Journal Entries
- Record only adjustments to book balance
- Should always contain cash account.
- Each adjustment affects another financial statement account.

Example: Bank Reconciliation
ABC Inc. just received its June 30th bank statement. According to the bank statement the company has $24,205.88 in cash but according to the company's ledger the cash balance is $26,326.60.
The following information is available:
- Cheque number 345 for $1,540.43 is still outstanding.
- Cheque number 341 was incorrectly debited from the account as $704.40 instead of $658.85.
- Bank memo states that a wire transfer of $1,000 was received from a customer who was paying off a previous purchase.
- Earned interest of $100 on account balance.
- Received a cheque from a customer for $745.60 but the cheque has not yet been deposited.
- Customer's cheque for $350 returned as NSF, bank charged ABC Inc. $20 service fee.
- Bookkeeper incorrectly recorded a cash purchase of inventory as $400 instead of $4,000.
Prepare the bank reconciliation statement and adjusting journal entries on June 30th.