
Journal Entry: Interest Accrual
At the end of the accounting period, any accrued interest on bonds must be expensed in an adjusting journal entry.
Accruing Interest
- Debit Interest expense: the portion of the next interest expense that has already been accrued (has already passed).
- Credit: Interest payable: the portion of the next interest payment that has already been accrued.
- Debit/Credit Premium or Discount: the difference between the expense the and payment.

Recording a payment following an accrual
- Debit Interest expense: the portion of the interest expense incurred after the accrual date.
- Debit Interest payable: the interest payable from the accrual date.
- Credit Cash: the complete coupon payment
- Debit/Credit Premium or Discount: the amount remaining to balance the journal entry.


Example: Accruing Interest
ABC Inc. issued a 5-year semi-annual bond with a coupon rate of 10% and a face value of $100,000. The market rate at issuance was 8% and the company's fiscal year ends on December 31.
Using the amortization table, prepare the journal entry to record the accrual of interest on December 31st, 2020 and the coupon payment on February 1st, 2021.

Journal entry to record the accrual of interest on December 31st, 2020

Journal entry to record the coupon payment on February 1st, 2021.


Example: Recording Bond Interest Accrual
United Airlines issued bonds with a face value of $250,000 and a coupon rate of 5%, coupons are paid semi-annually. The bonds mature in 10 years and at the time of issuance the market rate was 7%. Prepare the journal entry to record the accrual of interest on December 31, 2020 and the coupon payment on March 1st, 2021.
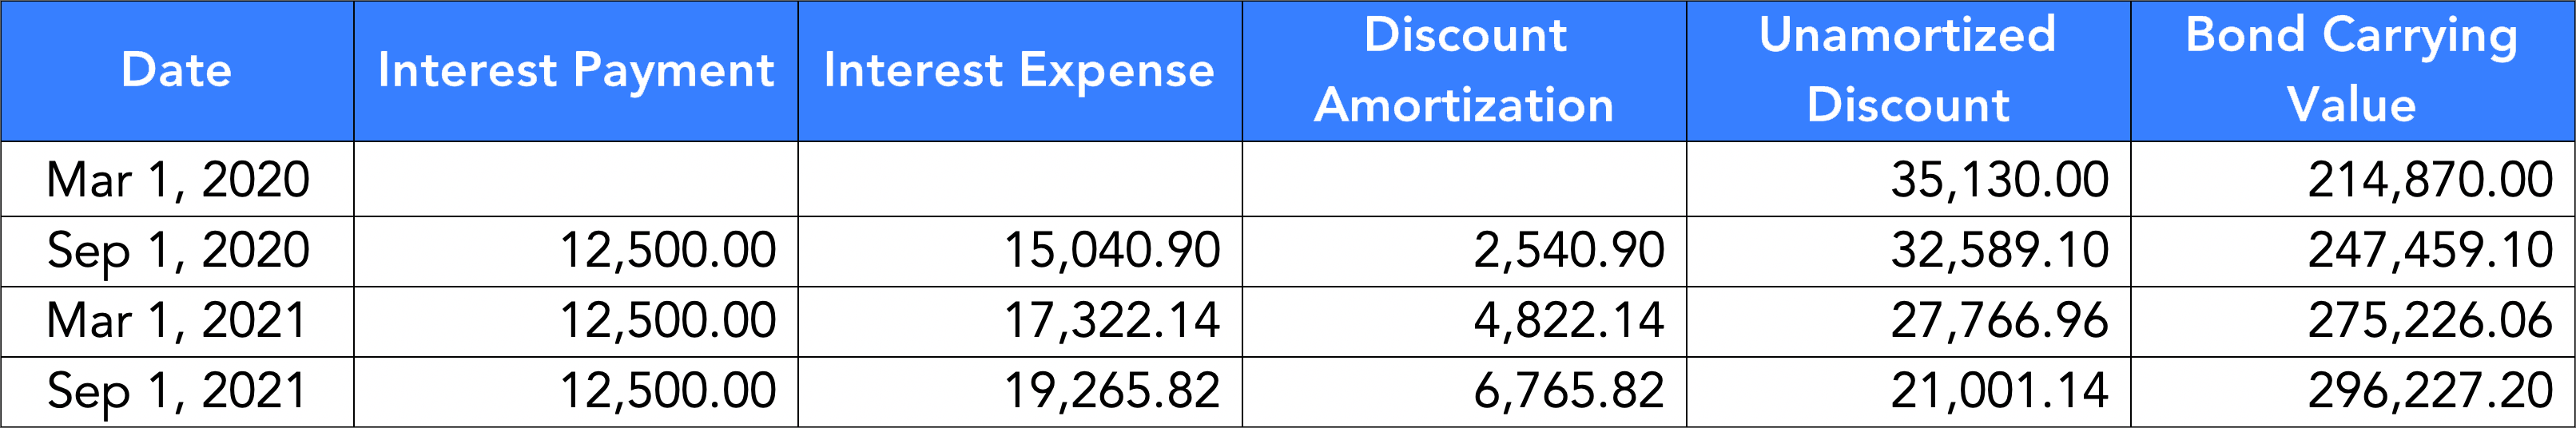
Journal entry to record the accrual of interest on December 31st, 2020
Journal entry to record the coupon payment on March 1st, 2021.