
Recording Cost of Goods Sold (Periodic)
Since inventory and cost of goods sold are not continuously updated under the periodic system, an adjusting journal entry is required at the end of the accounting period to bring these accounts up to date.
Computing Cost of Good Sold
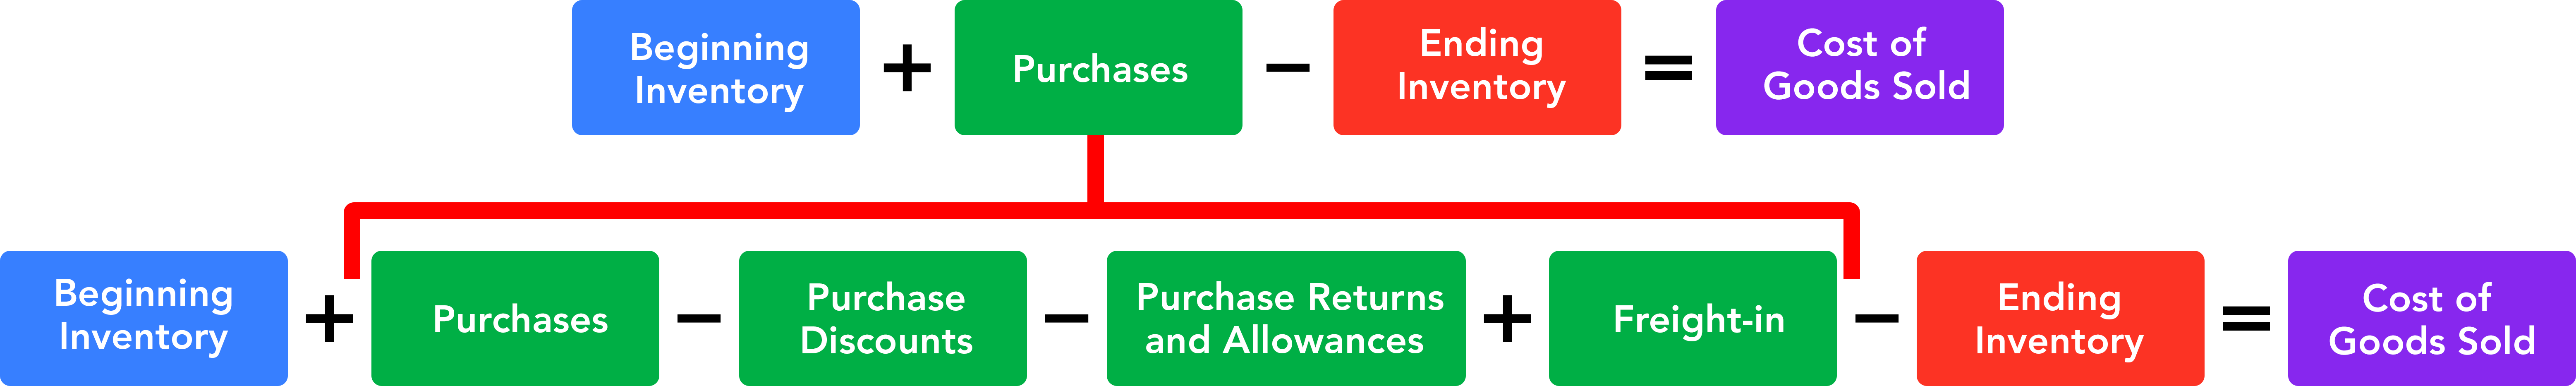
Adjusting Inventory and COGS
- Adjust beginning inventory to ending inventory
- Debit COGS using formula to find the amount
- Reduce all temporary accounts to zero
- Purchases: ________
- Purchase discounts: ________
- Purchase returns and allowances: ________
- Freight-in: ________

Example: Recording Cost of Goods Sold (Periodic)
Prepare the adjusting journal entry to record cost of goods sold at the end of the year.
Additional information:
- Beginning inventory: $40,000
- Purchases: $90,000
- Purchase returns and allowances: $5,000
- Purchase discounts: $3,500
- Freight in: $750
- Ending inventory: $48,500
