
Bond Valuation
The coupon payment is the periodic interest payment the bondholder (investor) will receive from the issuer (borrower). This is calculated by multiplying the coupon rate by the face value of the bond and then dividing it by the number of payments per year (typically annual or semi-annual).
Step 1: Compute the periodic coupon payment
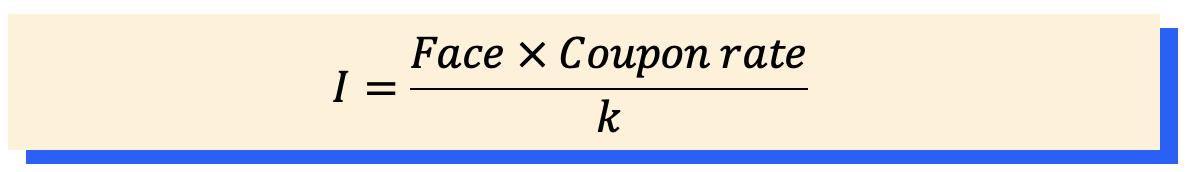
Where:
coupon payment (in dollars)
Face value of the bond
coupon rate (in %)
number of payments per year
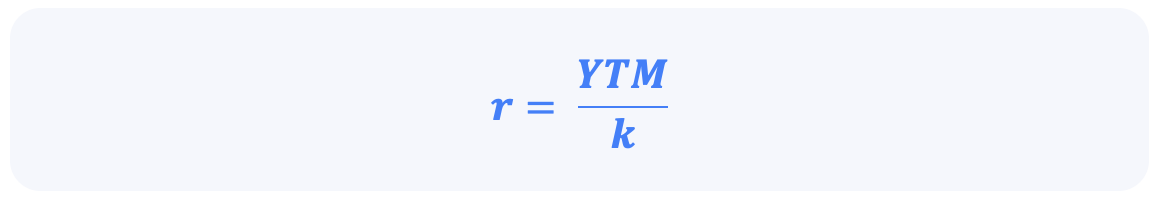
Step 2: Computing the Periodic Discount Rate
The discount rate used to compute the price of the bond is the yield to maturity (YTM) divided by the number of coupon payments per year.
Step 3: Compute the Present Value of the Coupon Payments and the Present Value of the Face Value
Using the Formula
Structurally a bond is nothing more than a stream of equal coupon payments (annuity) and a face value amount at the maturity date (future value)
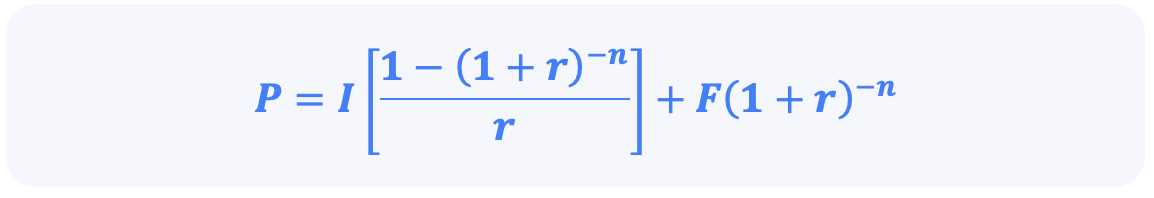
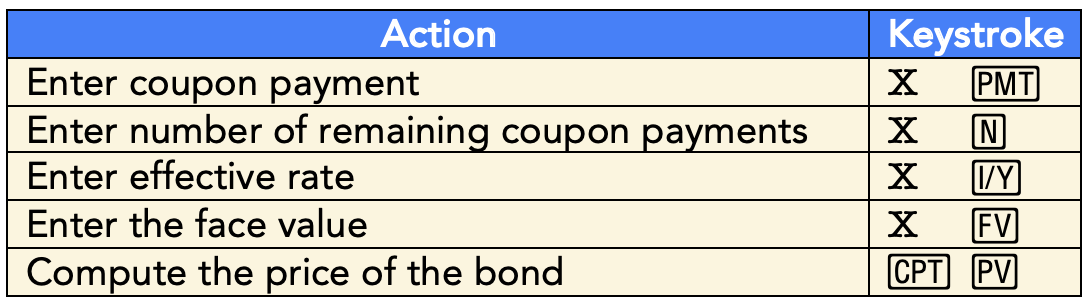
Using the Financial Calculator
Example: Bond Valuation
Two years ago, Golden Residential Real Estate Investment Trust (“Golden”) issued coupon bond securities to raise capital. The face value of each bond is $1,000. The coupon rate is 10%; coupons are paid on an annual basis. The term was 10 years. The current market effective annual rate is 5%. What is the current price of a Golden coupon bond security?

Example: Bond Valuation
Seattle Dairy Cooperative has issued 25-year bond securities —each of which has a face value of $1,000. The bond securities offer a coupon rate of 5% and pays coupons on a semi-annual basis. Main Street Journal reports a YTM of 4%. What is the current price of each bond security?