Manufacturing and Merchandising Budgets
Manufacturing Companies
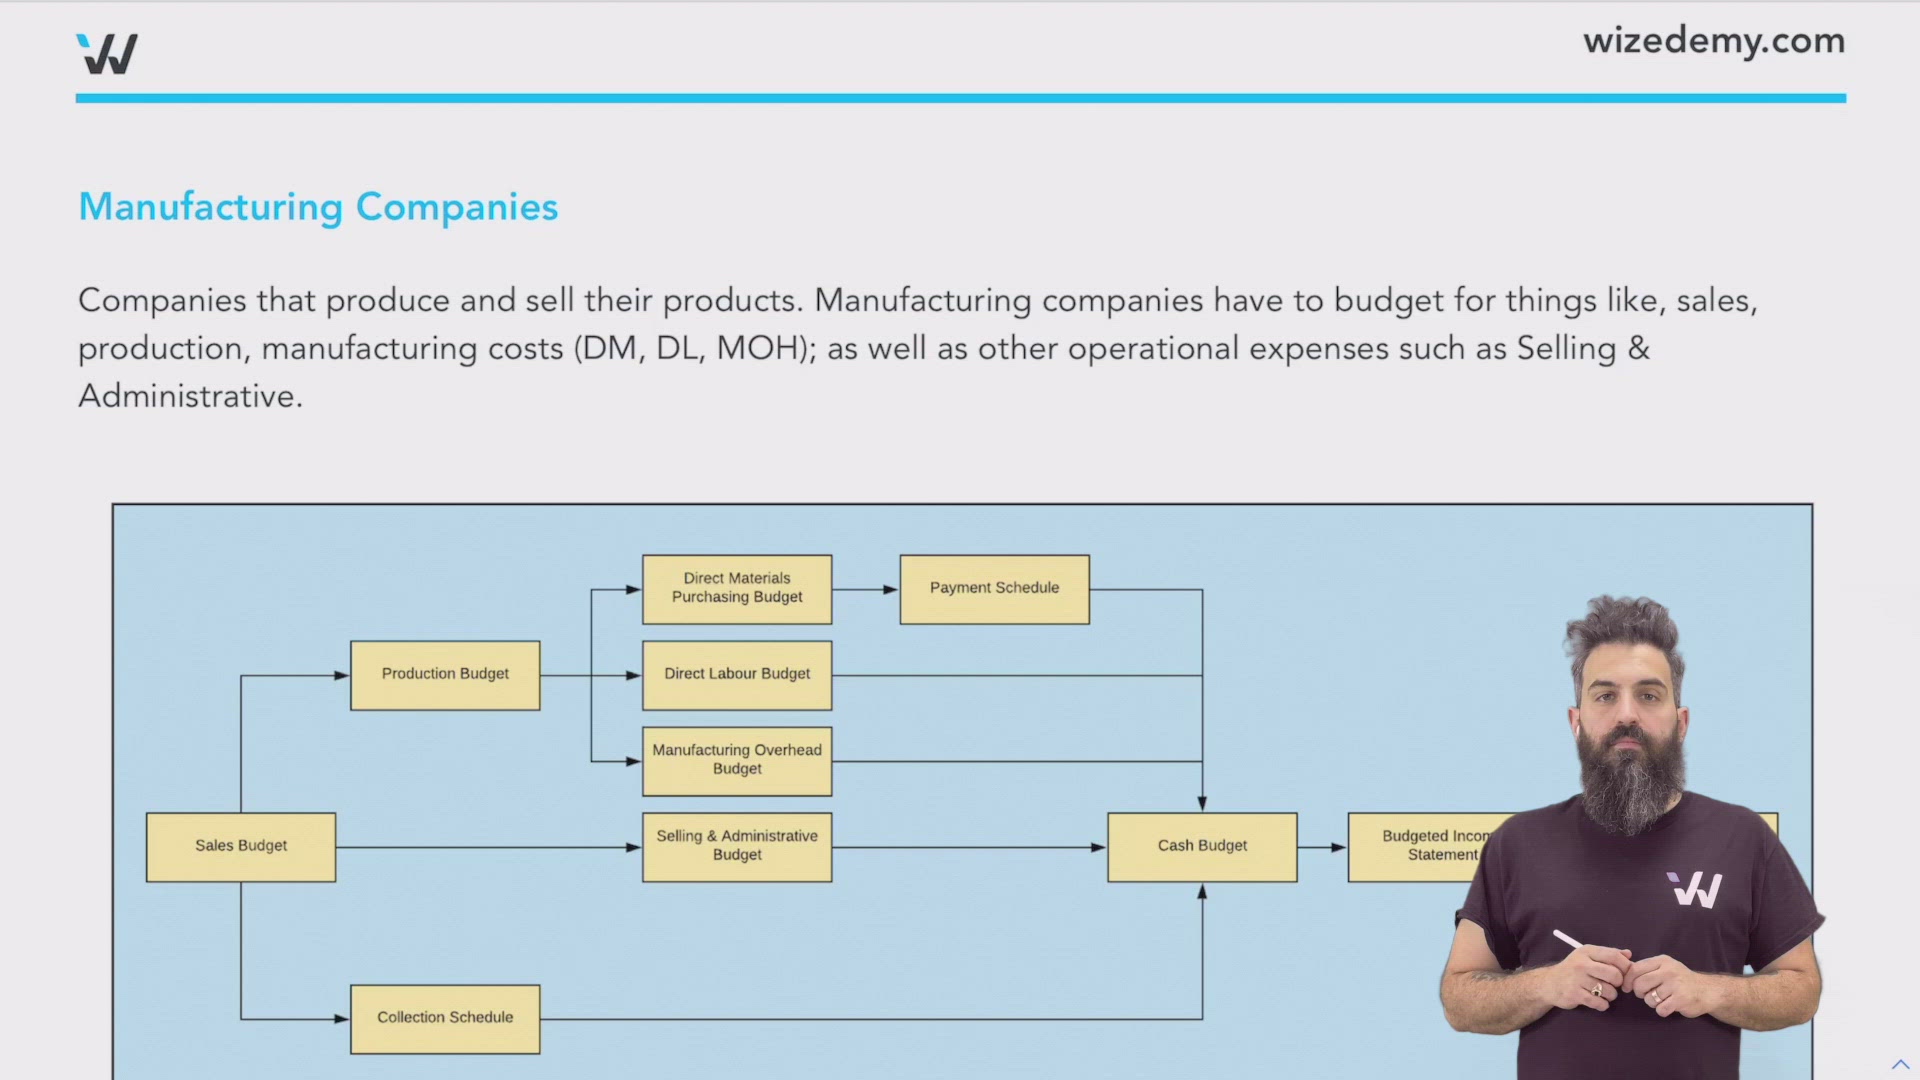
Companies that produce and sell their products. Manufacturing companies have to budget for things like, sales, production, manufacturing costs (DM, DL, MOH); as well as other operational expenses such as Selling & Administrative.
Merchandising Companies
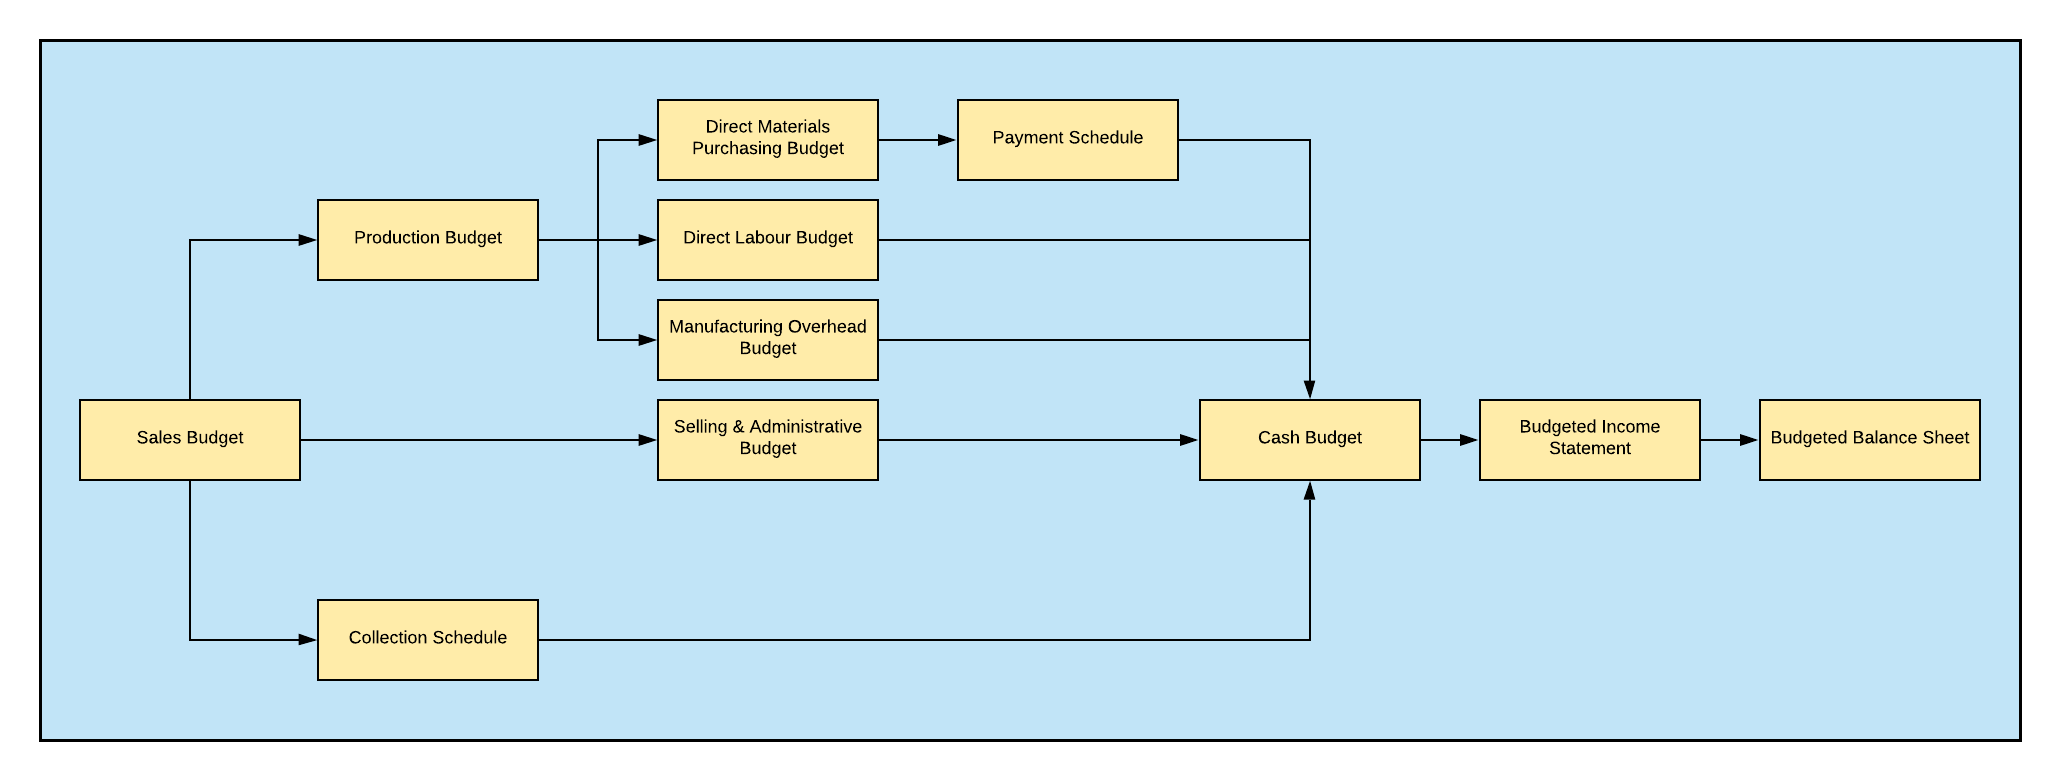
Merchandising companies purchase their inventory from suppliers are resell it to customers. There are fewer budgets because there is no need to budget for materials, labour and overhead.
The Sales Budget
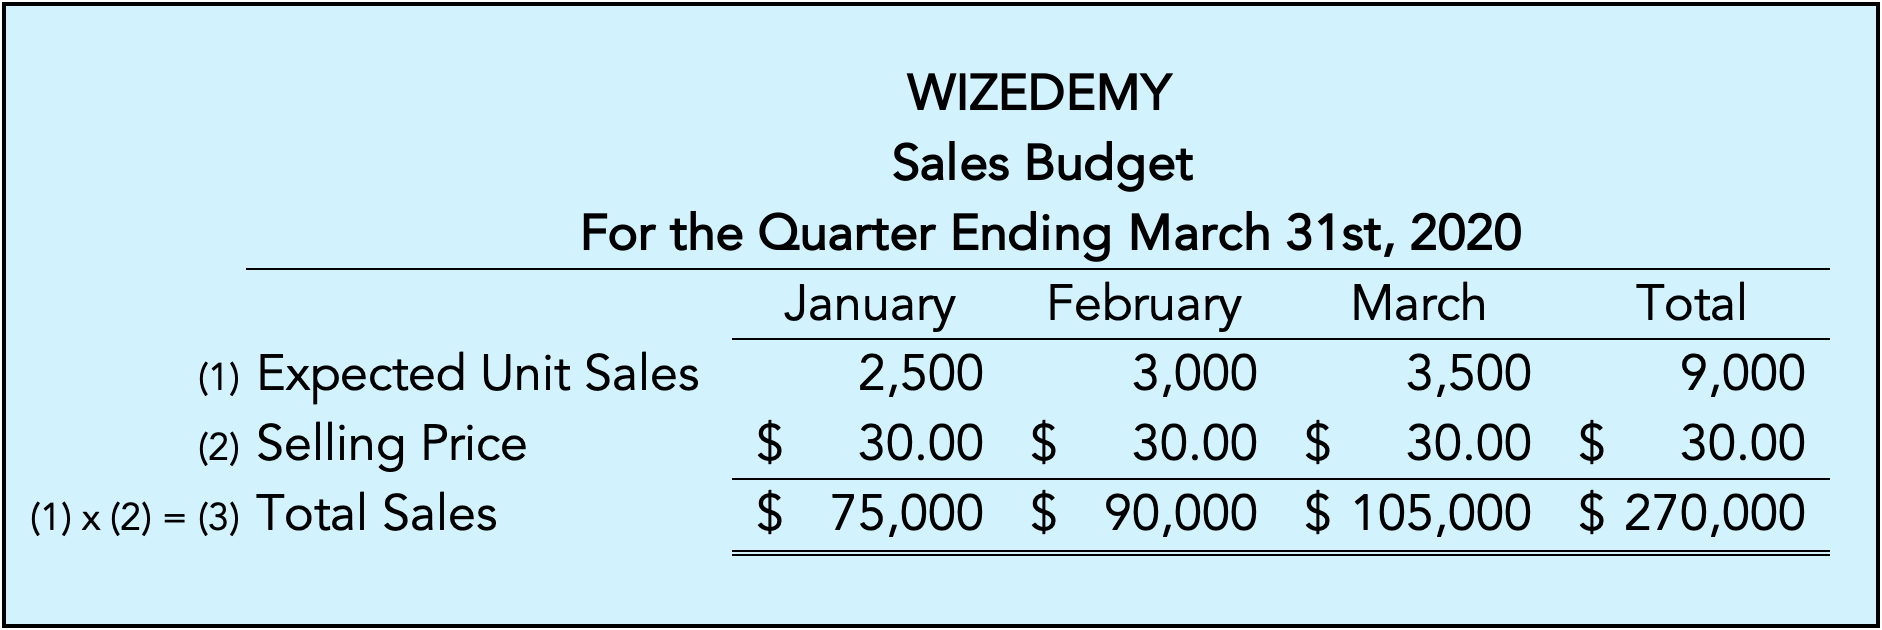
The sales budget is the first step in preparing a master budget. It serves to predict what sales will be in the budgeted periods by multiplying the expected number of unit sales by the expected selling price.
The Collection Schedule
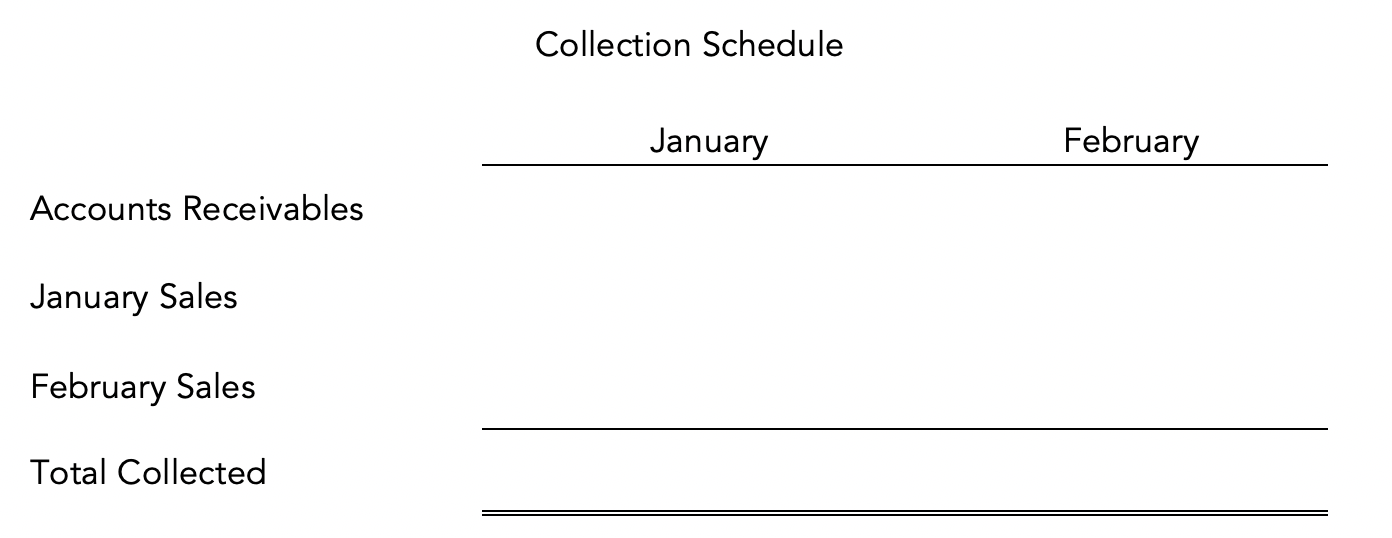
The collection schedule is an extension of the sales budget that outlines when the company will receive the cash for the sales it has made. The schedule is based on expectations about how and when customers will pay and can be very simply or fairly complex.
Simple Collection Schedule
ABC Inc collects 40% of its sales in the month of sale and 60% the month after.
Complex Collection Schedule
ABC Inc's sales are 30% in cash and 70% on account. 20% of the accounts receivables are collected in the month of sale, 40% the month following the sale, 30% the second month following the sale and the rest are bad debt.
For Example
Wizedemy sold 2,000 units in December of 2019, it expects sales will increase by 500 units per month moving forward and units are sold for $30 each. 60% of sales are made in cash and the rest on account, of the sales on account, 30% are collected in the month of sale, 65% the month after and 5% are bad debt.

Example: Sales Budget and Collection Schedule
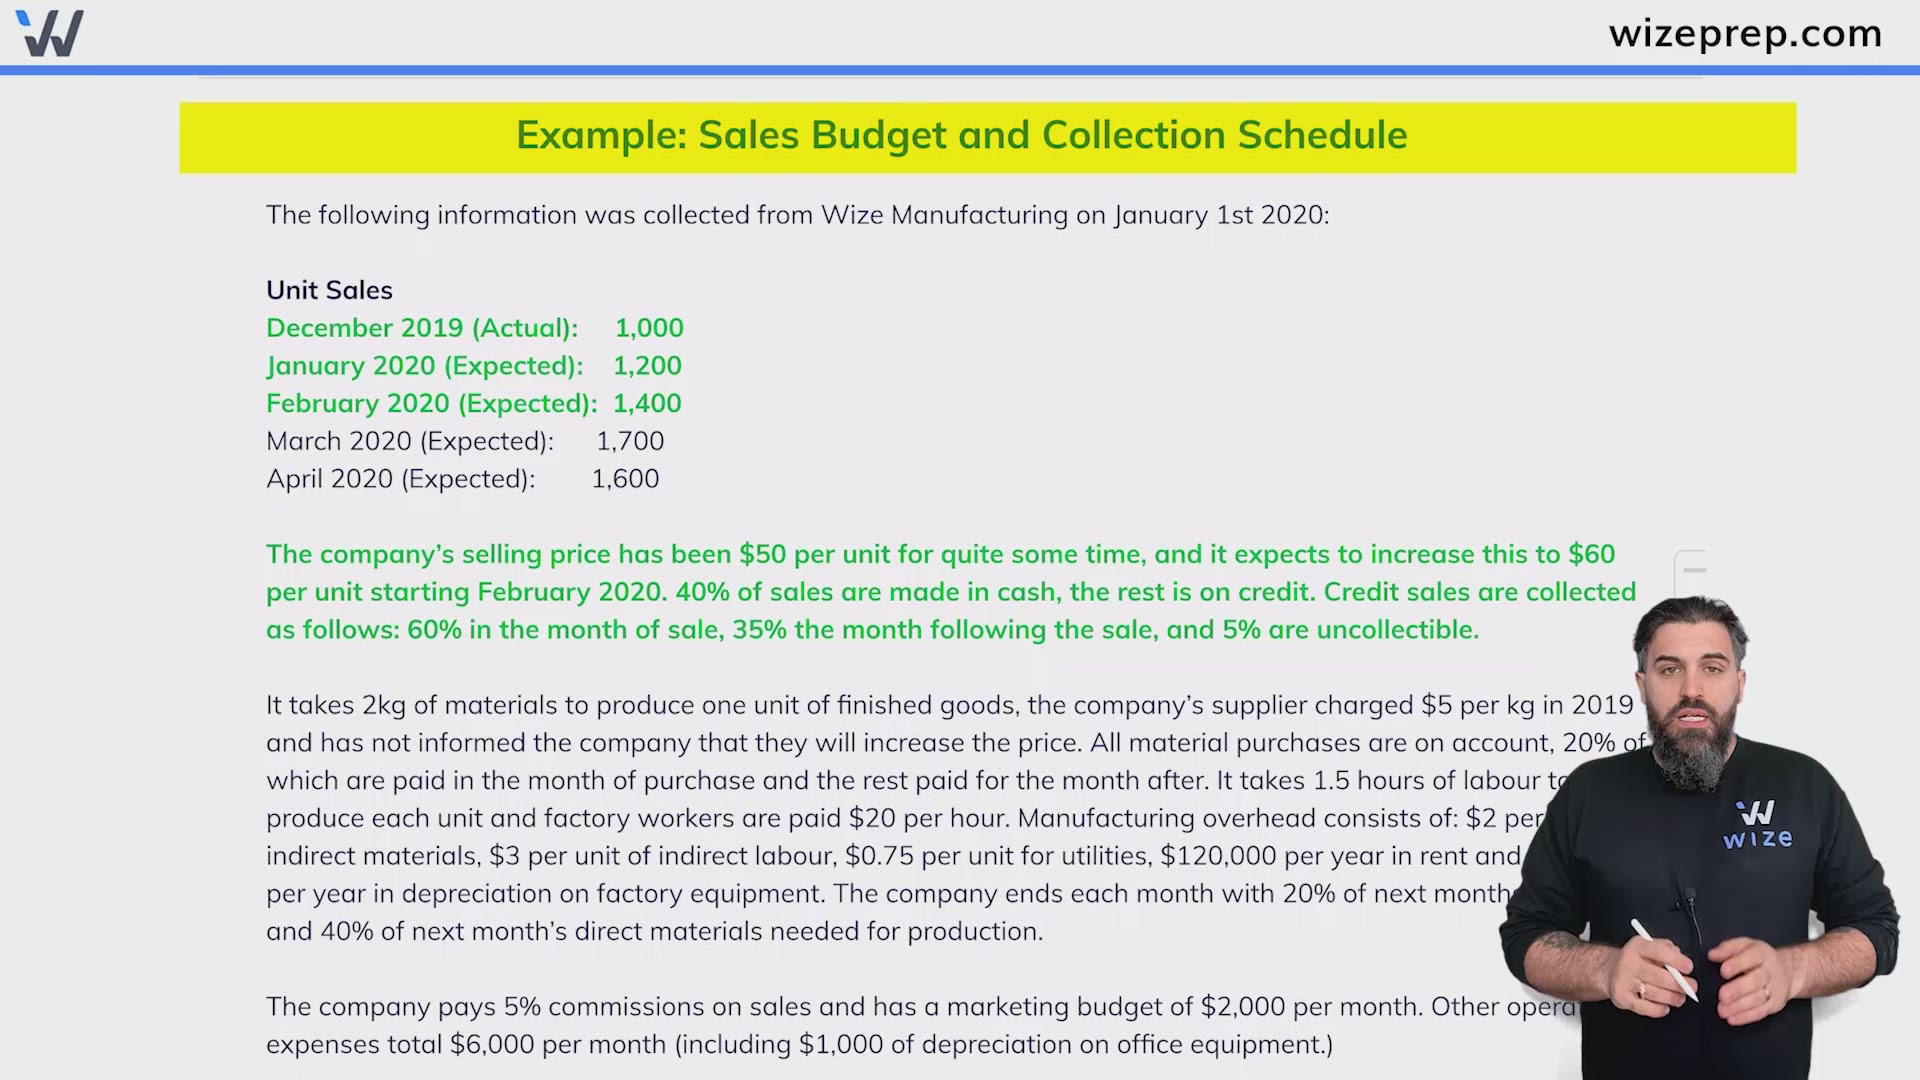
The following information was collected from Wize Manufacturing on January 1st 2020:
Unit Sales
December 2019 (Actual): 1,000
January 2020 (Expected): 1,200
February 2020 (Expected): 1,400
March 2020 (Expected): 1,700
April 2020 (Expected): 1,600
The company’s selling price has been $50 per unit for quite some time, and it expects to increase this to $60 per unit starting February 2020. 40% of sales are made in cash, the rest is on credit. Credit sales are collected as follows: 60% in the month of sale, 35% the month following the sale, and 5% are uncollectible.
It takes 2kg of materials to produce one unit of finished goods, the company’s supplier charged $5 per kg in 2019 and has not informed the company that they will increase the price. All material purchases are on account, 20% of which are paid in the month of purchase and the rest paid for the month after. It takes 1.5 hours of labour to produce each unit and factory workers are paid $20 per hour. Manufacturing overhead consists of: $2 per unit of indirect materials, $3 per unit of indirect labour, $0.75 per unit for utilities, $120,000 per year in rent and $60,000 per year in depreciation on factory equipment. The company ends each month with 20% of next months unit sales and 40% of next month’s direct materials needed for production.
The company pays 5% commissions on sales and has a marketing budget of $2,000 per month. Other operating expenses total $6,000 per month (including $1,000 of depreciation on office equipment.)
The company plans to issue 5,000 new shares for $10 per share in February 2019 and It plans on purchasing a new piece of equipment for $60,000 in January; and it plans on declaring and paying a dividend of $10,000 in January.
The company ended 2019 with $16,000 in cash, $10,000 in net accounts receivable and $12,000 in accounts payable. Ending direct materials inventory was zero in 2019, and the company’s minimum cash balance is $15,000. Borrowings are made in multiples of $500 and the company’s line of credit carries a 12% annual interest rate. Borrowings are made at the beginning of the month and repayments are made the end of the month.
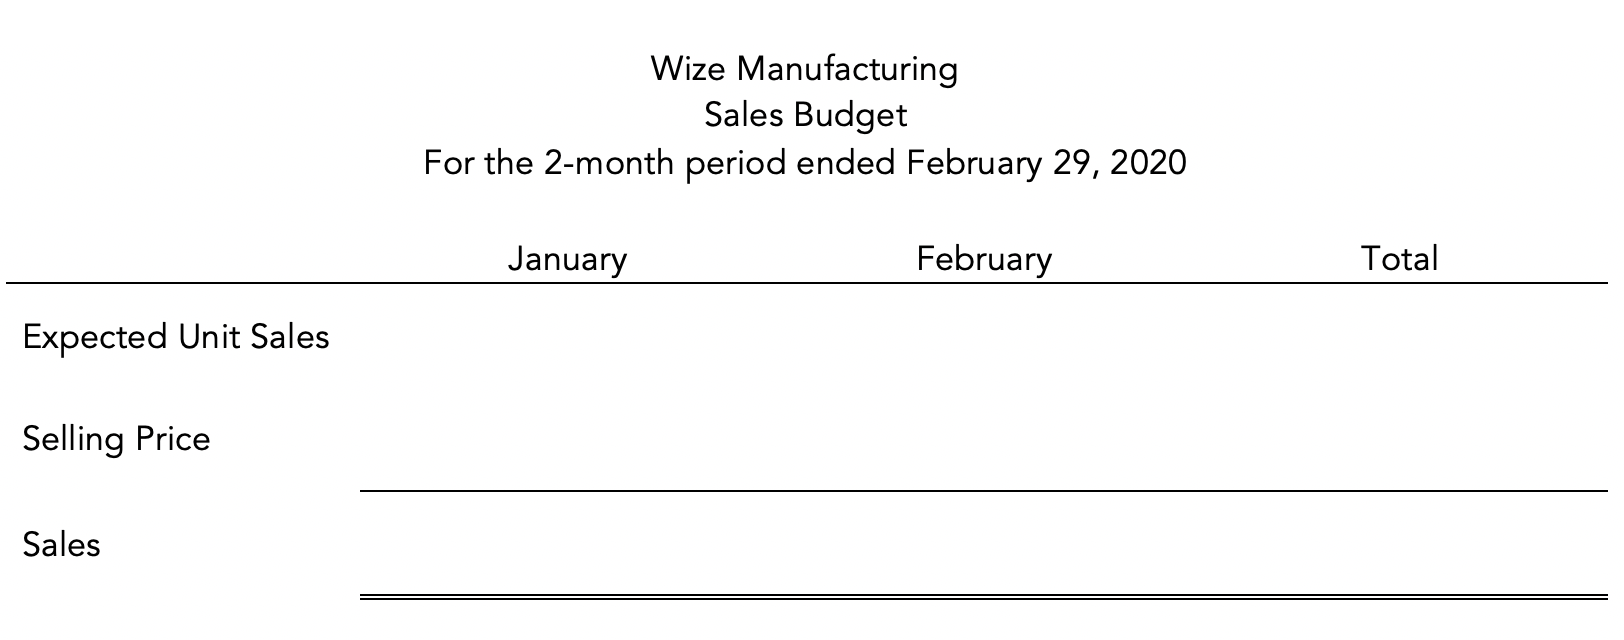
Prepare the sales budget and collection schedule for the first 2 months of 2020
The Production Budget
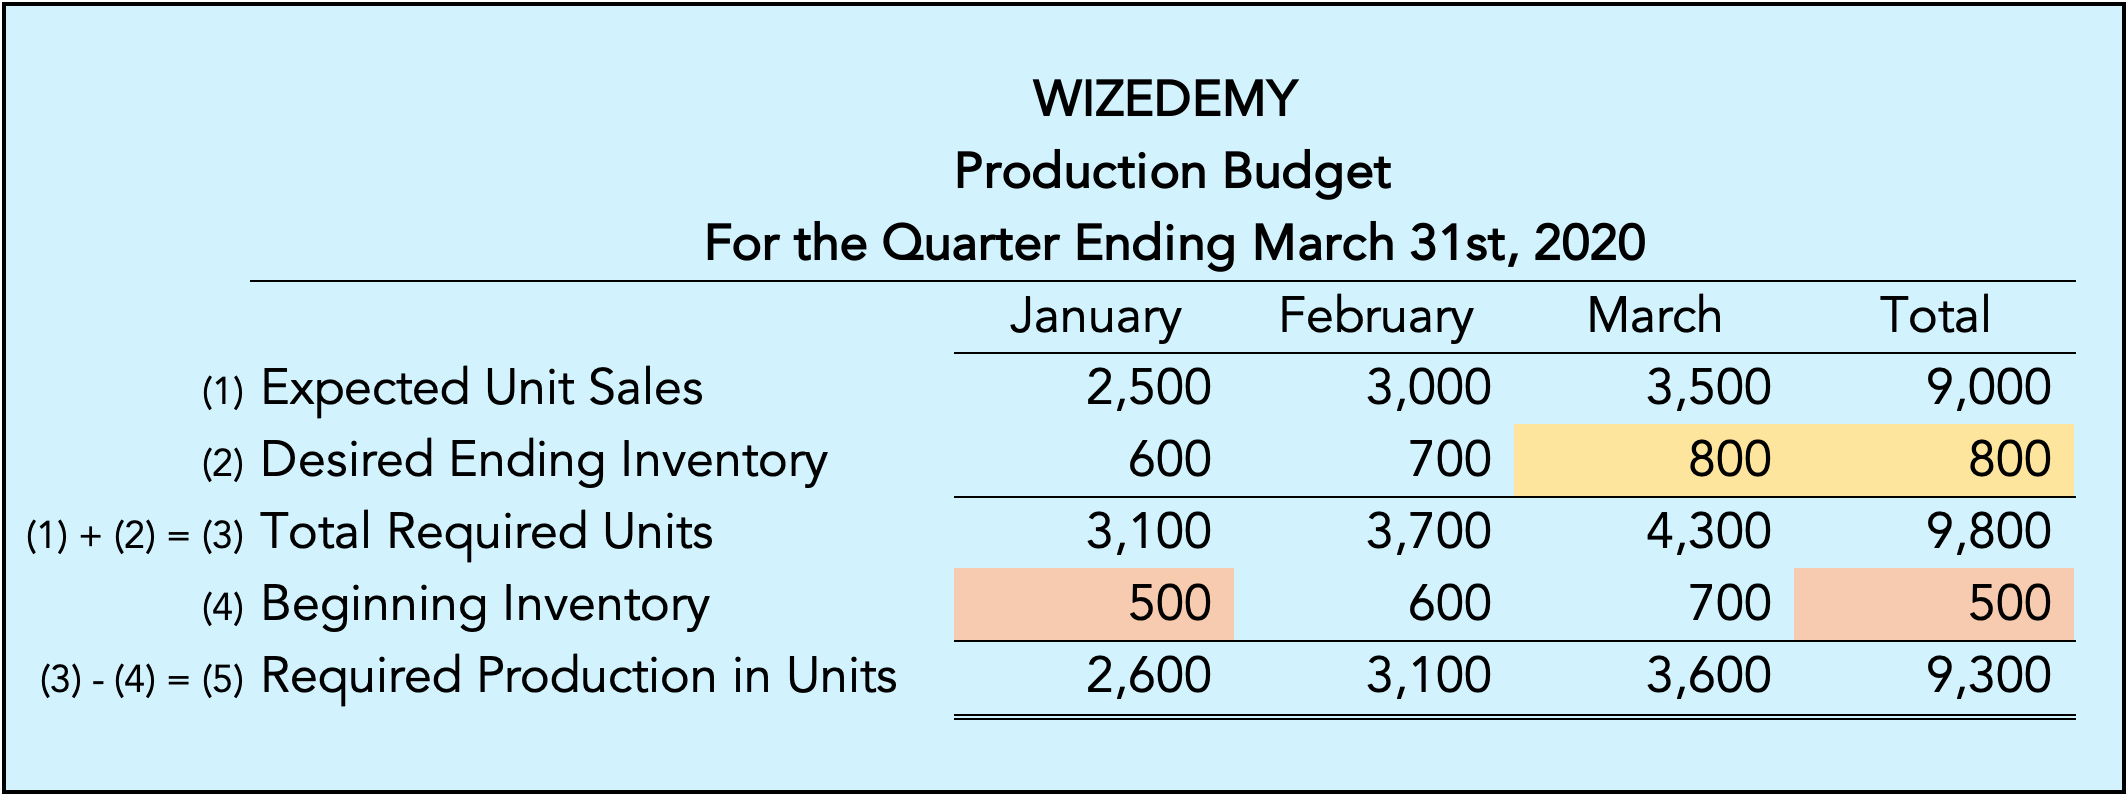
The purpose of a production budget is to forecast the number of units that the company needs to produce in the upcoming periods. It is based on the following formula:
Expected Sales + Desired Ending Inventory - Beginning Inventory = Production
Desired Ending Inventory
Company's will typically maintain a certain ending inventory at the end of each period that is based on the following periods sales. This will ensure a smooth operation and decrease the chance of a stock out if there are delays in production. This is often expressed as a percentage of the following period's sales.

Example: The Production Budget
The following information was collected from Wize Manufacturing on January 1st 2020:
Unit Sales
December 2019 (Actual): 1,000
January 2020 (Expected): 1,200
February 2020 (Expected): 1,400
March 2020 (Expected): 1,700
April 2020 (Expected): 1,600
The company’s selling price has been $50 per unit for quite some time, and it expects to increase this to $60 per unit starting February 2020. 40% of sales are made in cash, the rest is on credit. Credit sales are collected as follows: 60% in the month of sale, 35% the month following the sale, and 5% are uncollectible.
It takes 2kg of materials to produce one unit of finished goods, the company’s supplier charged $5 per kg in 2019 and has not informed the company that they will increase the price. All material purchases are on account, 20% of which are paid in the month of purchase and the rest paid for the month after. It takes 1.5 hours of labour to produce each unit and factory workers are paid $20 per hour. Manufacturing overhead consists of: $2 per unit of indirect materials, $3 per unit of indirect labour, $0.75 per unit for utilities, $120,000 per year in rent and $60,000 per year in depreciation on factory equipment. The company ends each month with 20% of next months unit sales and 40% of next month’s direct materials needed for production.
The company pays 5% commissions on sales and has a marketing budget of $2,000 per month. Other operating expenses total $6,000 per month (including $1,000 of depreciation on office equipment.)
The company plans to issue 5,000 new shares for $10 per share in February 2019 and It plans on purchasing a new piece of equipment for $60,000 in January; and it plans on declaring and paying a dividend of $10,000 in January.
The company ended 2019 with $16,000 in cash, $10,000 in net accounts receivable and $12,000 in accounts payable. Ending direct materials inventory was zero in 2019, and the company’s minimum cash balance is $15,000. Borrowings are made in multiples of $500 and the company’s line of credit carries a 12% annual interest rate. Borrowings are made at the beginning of the month and repayments are made the end of the month.
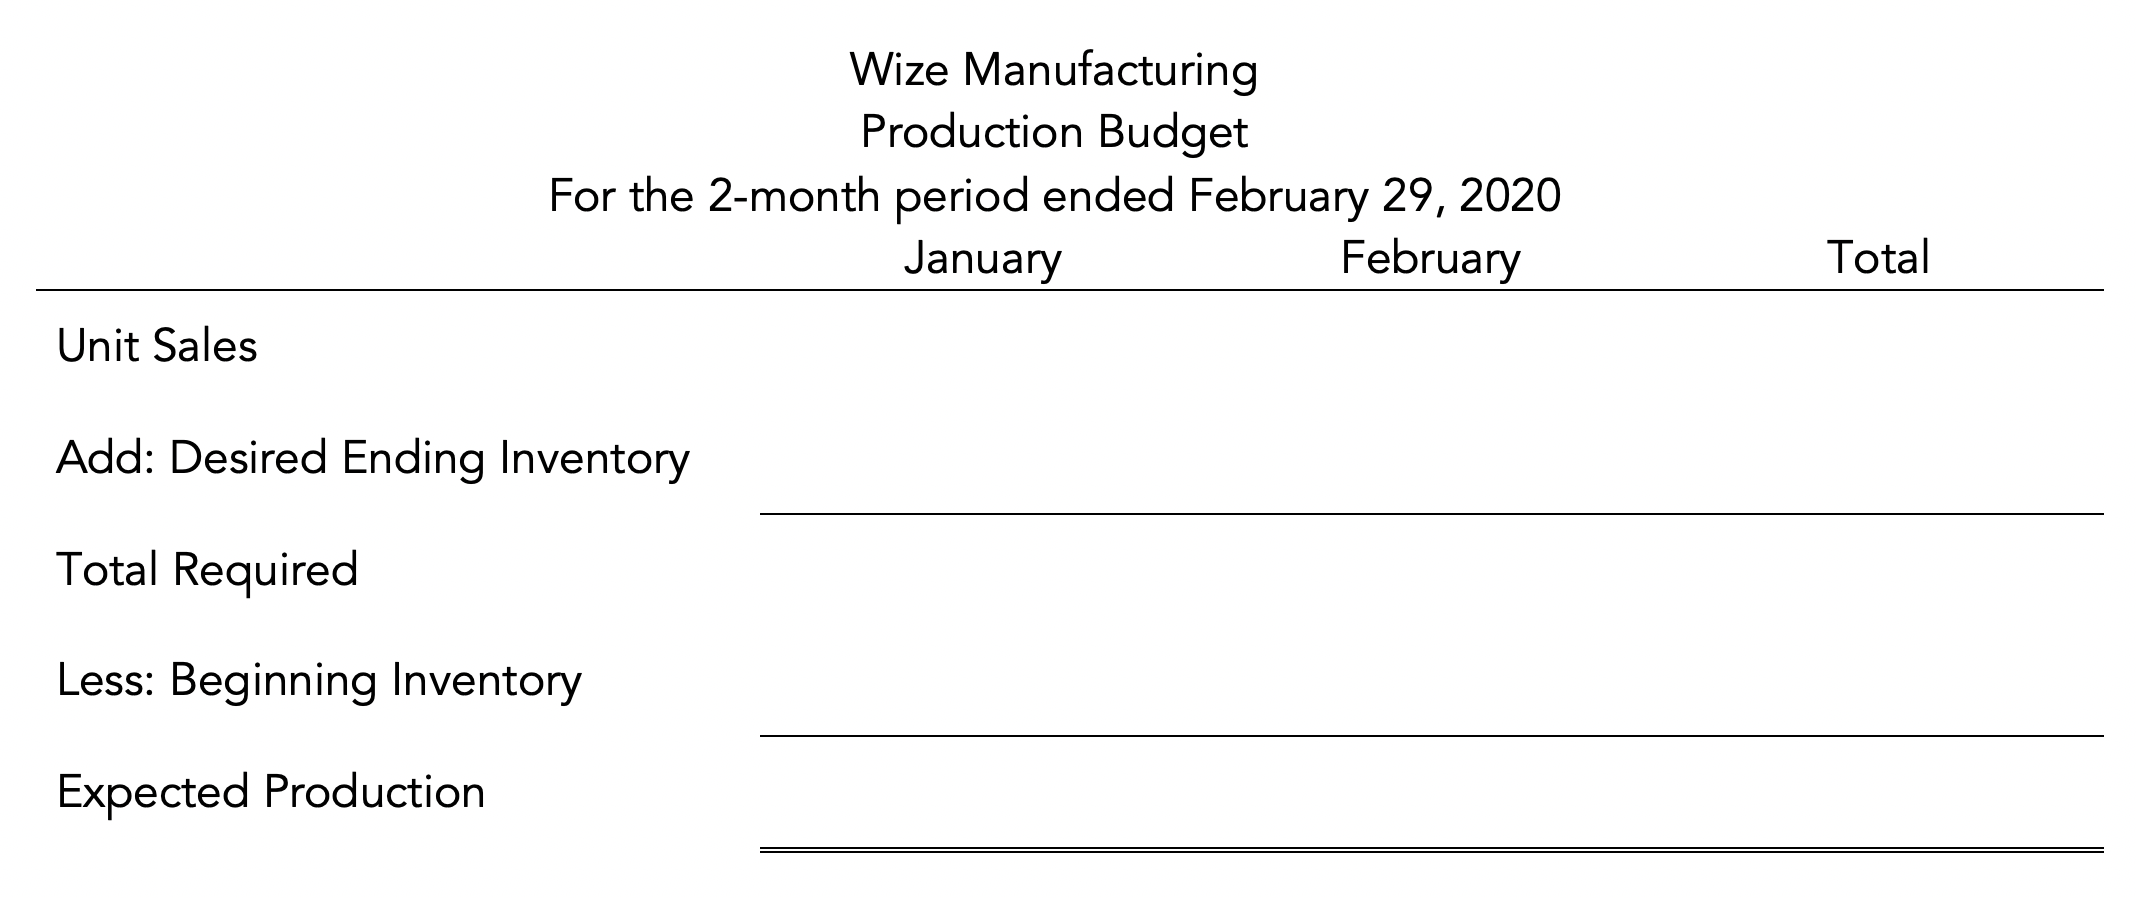
Prepare the production budget for the first 2 months of 2020
The Direct Materials Purchasing Budget
The purpose of this budget is to forecast the amount of materials that will be purchased in each of the budgeted periods. It begins where the production budget ends since the amount of materials needed is based on the amount of units that are expected to be produced.
The budget is based on the following formula:
DM Required for Production + Desired Ending DM Inventory - Beginning DM Inventory = DM Purchases
The Payment Schedule
The payment schedule outlines when the company expects to pay its suppliers' the cash for purchases. It is based on a predetermined payment pattern. For example, the company pays for half its purchases in the month of purchase and the rest in the following month.
Example
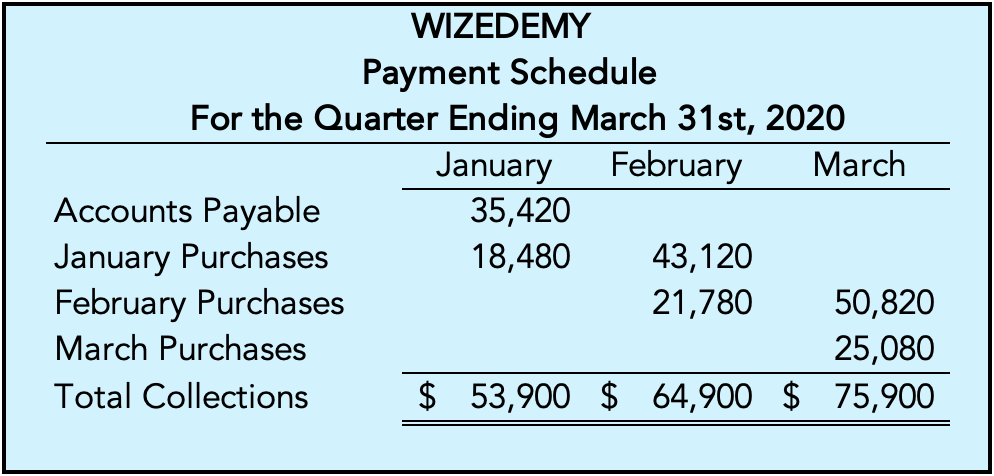
Wizedemy uses 2kg of direct materials for each unit of finished goods it produces, and expects to spend $11 per kg on materials. All purchases are on account and 30% is paid in the month of purchase while the rest is paid the month after.

Example: Direct Materials Purchasing Budget and Payment Schedule
The following information was collected from Wize Manufacturing on January 1st 2020:
Unit Sales
December 2019 (Actual): 1,000
January 2020 (Expected): 1,200
February 2020 (Expected): 1,400
March 2020 (Expected): 1,700
April 2020 (Expected): 1,600
The company’s selling price has been $50 per unit for quite some time, and it expects to increase this to $60 per unit starting February 2020. 40% of sales are made in cash, the rest is on credit. Credit sales are collected as follows: 60% in the month of sale, 35% the month following the sale, and 5% are uncollectible.
It takes 2kg of materials to produce one unit of finished goods, the company’s supplier charged $5 per kg in 2019 and has not informed the company that they will increase the price. All material purchases are on account, 20% of which are paid in the month of purchase and the rest paid for the month after. It takes 1.5 hours of labour to produce each unit and factory workers are paid $20 per hour. Manufacturing overhead consists of: $2 per unit of indirect materials, $3 per unit of indirect labour, $0.75 per unit for utilities, $120,000 per year in rent and $60,000 per year in depreciation on factory equipment. The company ends each month with 20% of next months unit sales and 40% of next month’s direct materials needed for production. Expected production in March is 1,680 units.
The company pays 5% commissions on sales and has a marketing budget of $2,000 per month. Other operating expenses total $6,000 per month (including $1,000 of depreciation on office equipment.)
The company plans to issue 5,000 new shares for $10 per share in February 2019 and It plans on purchasing a new piece of equipment for $60,000 in January; and it plans on declaring and paying a dividend of $10,000 in January.
The company ended 2019 with $16,000 in cash, $10,000 in net accounts receivable and $12,000 in accounts payable. Ending direct materials inventory was zero in 2019, and the company’s minimum cash balance is $15,000. Borrowings are made in multiples of $500 and the company’s line of credit carries a 12% annual interest rate. Borrowings are made at the beginning of the month and repayments are made the end of the month.
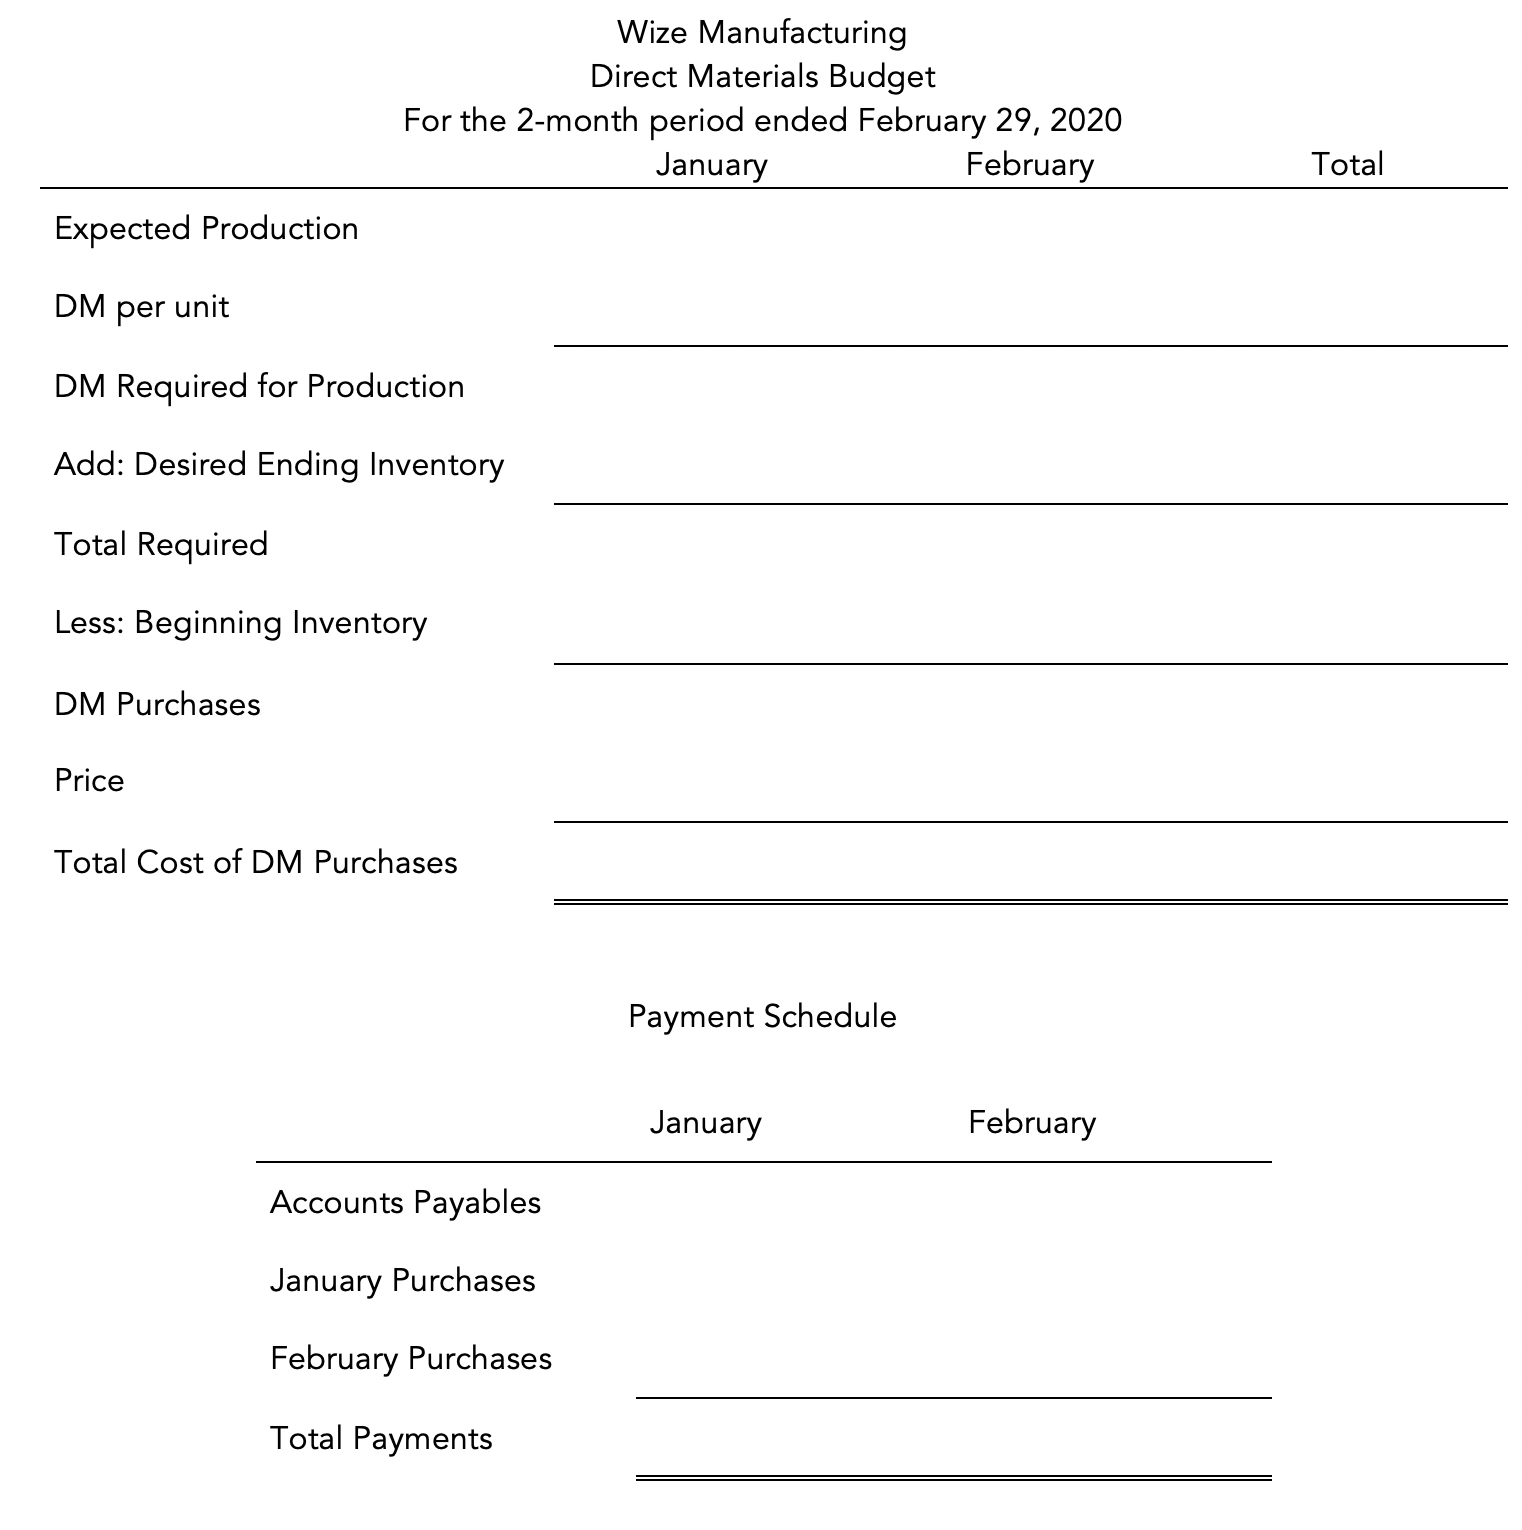
Prepare the Direct Materials Budget and Payment Schedule for the first 2 months of 2020
The Direct Labor Budget and Manufacturing Overhead Budget
Direct Labor Budget
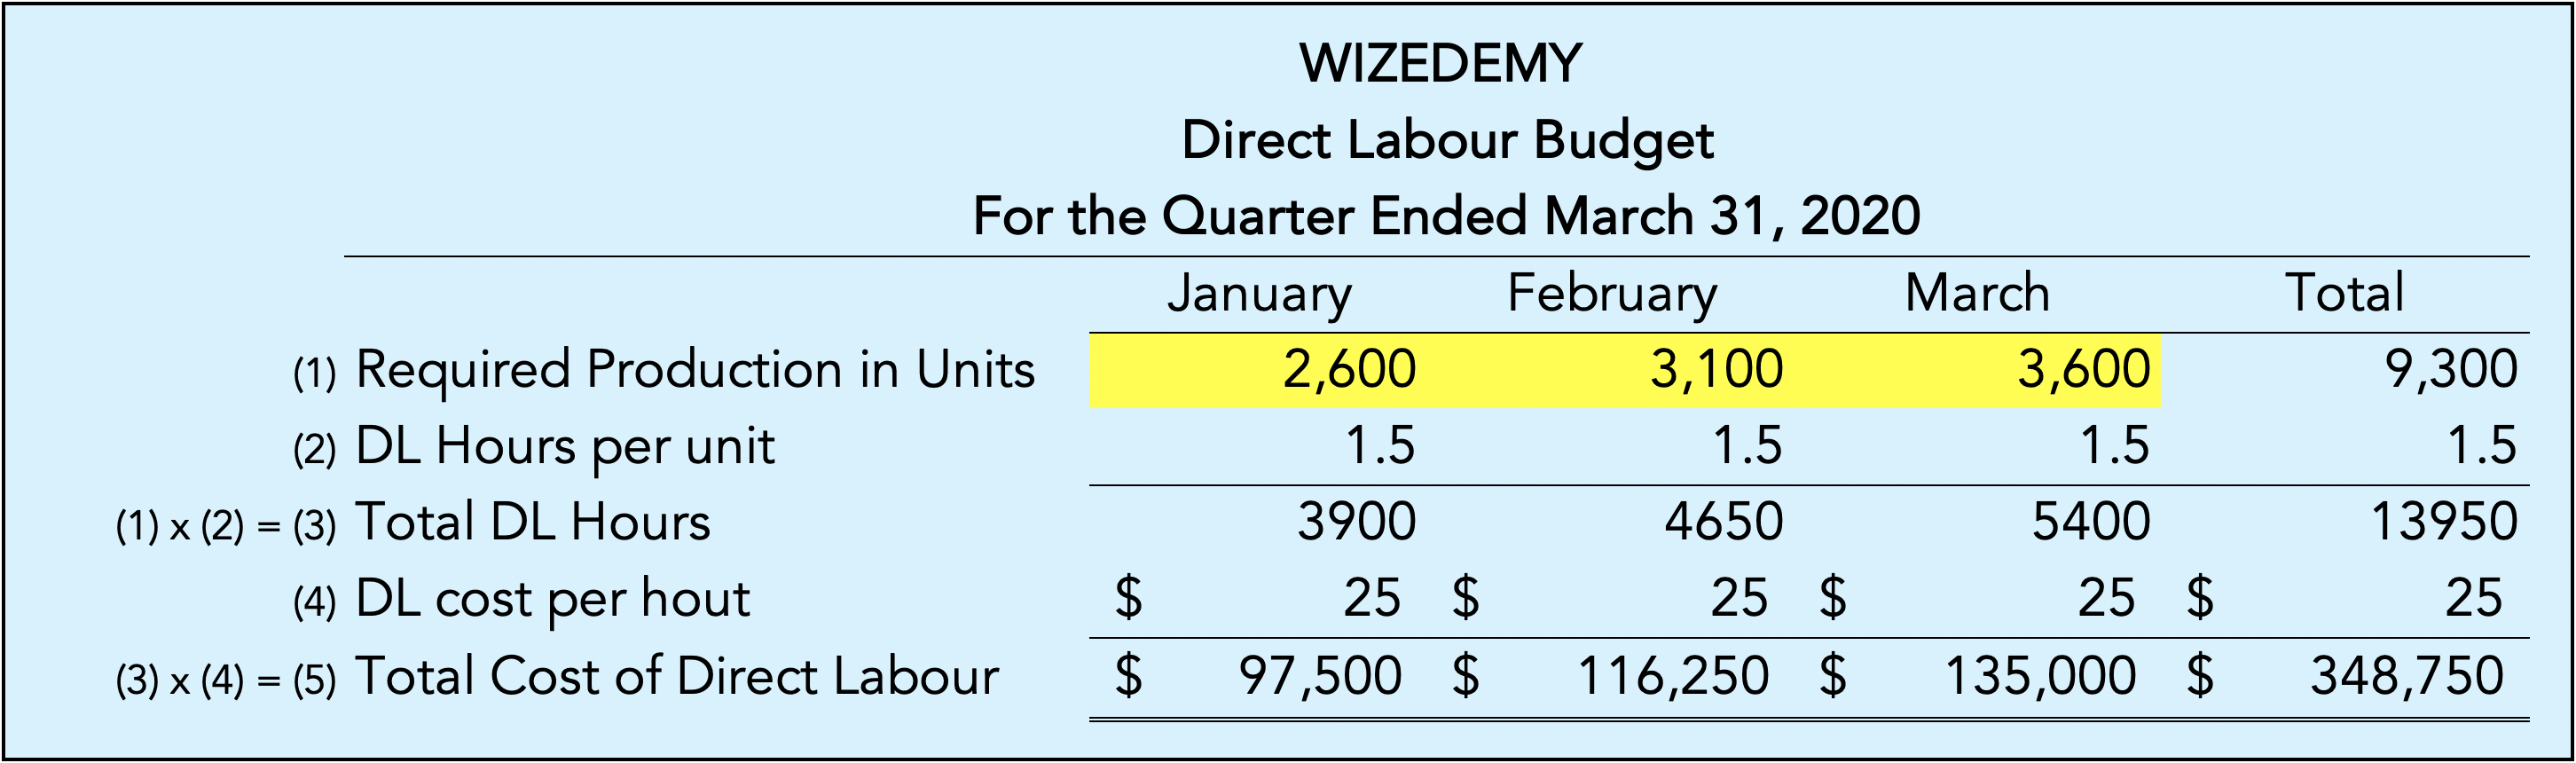
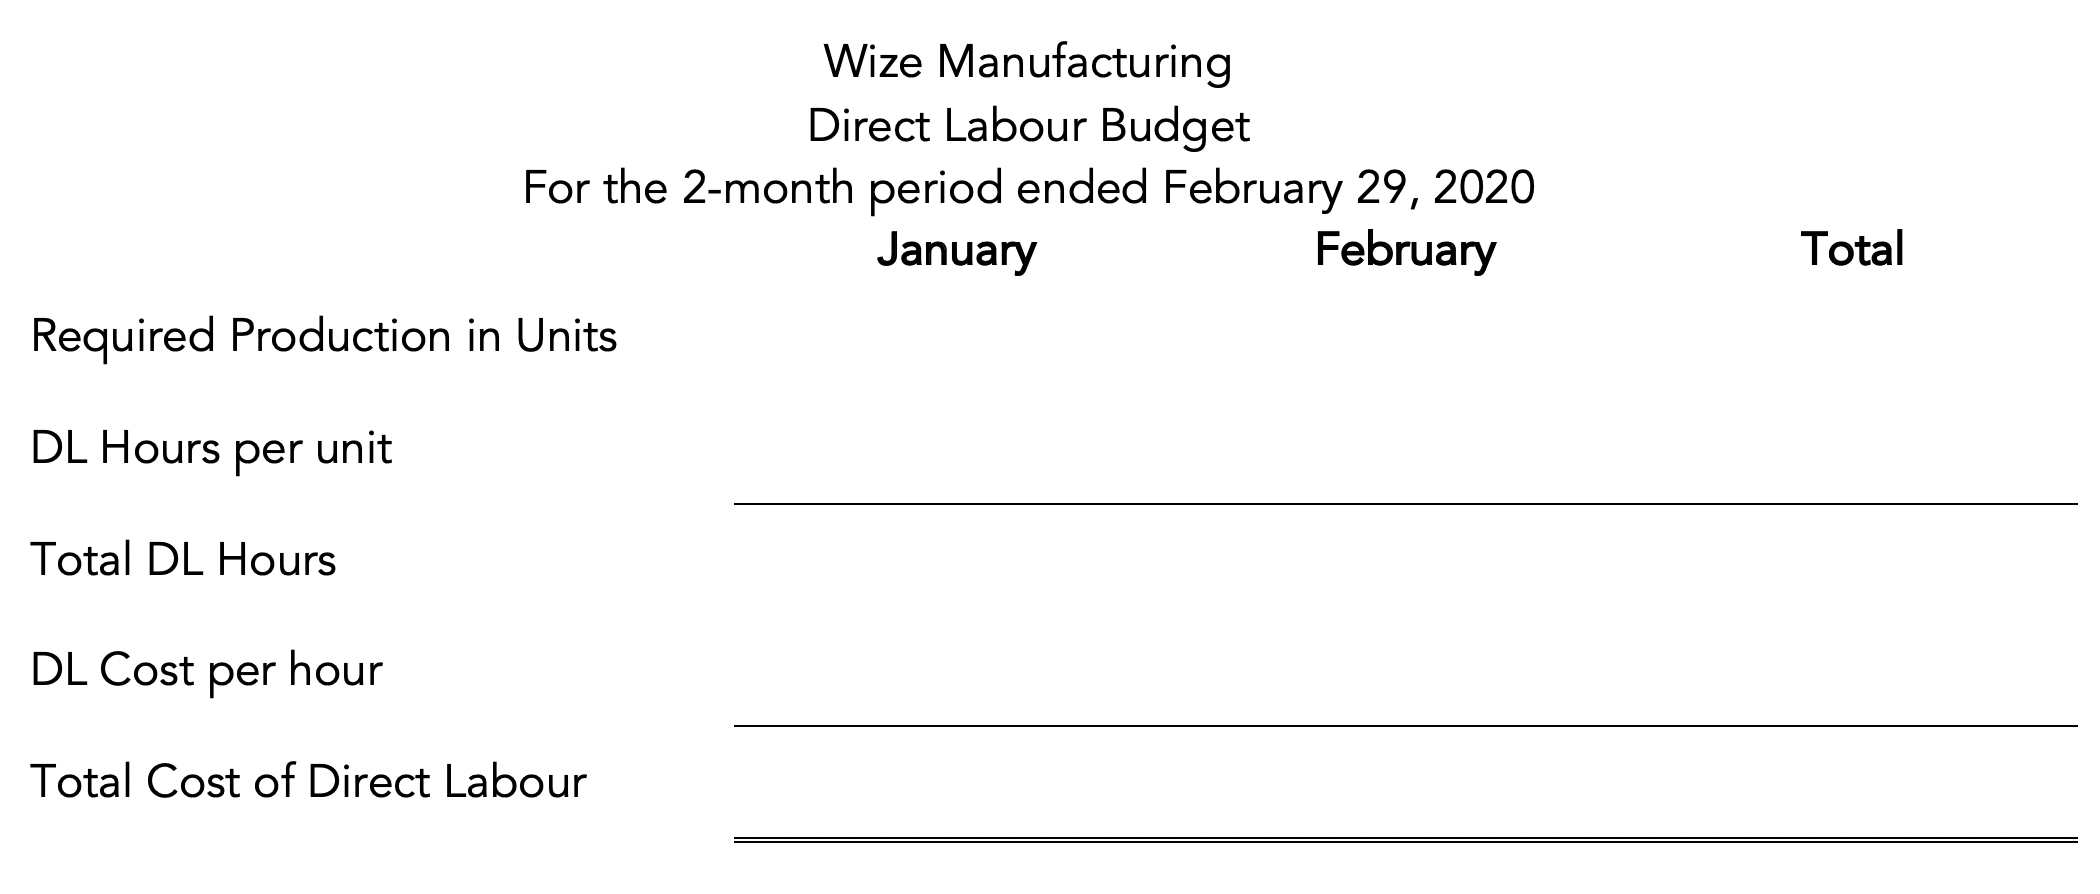
The purpose of the DL Budget is to forecast how much the company will spend on direct labour in the budgeted periods. It is based on the following formula:
Units Produced x DL Hours per unit x Hourly Wages = Cost of Direct Labour
Manufacturing Overhead Budget
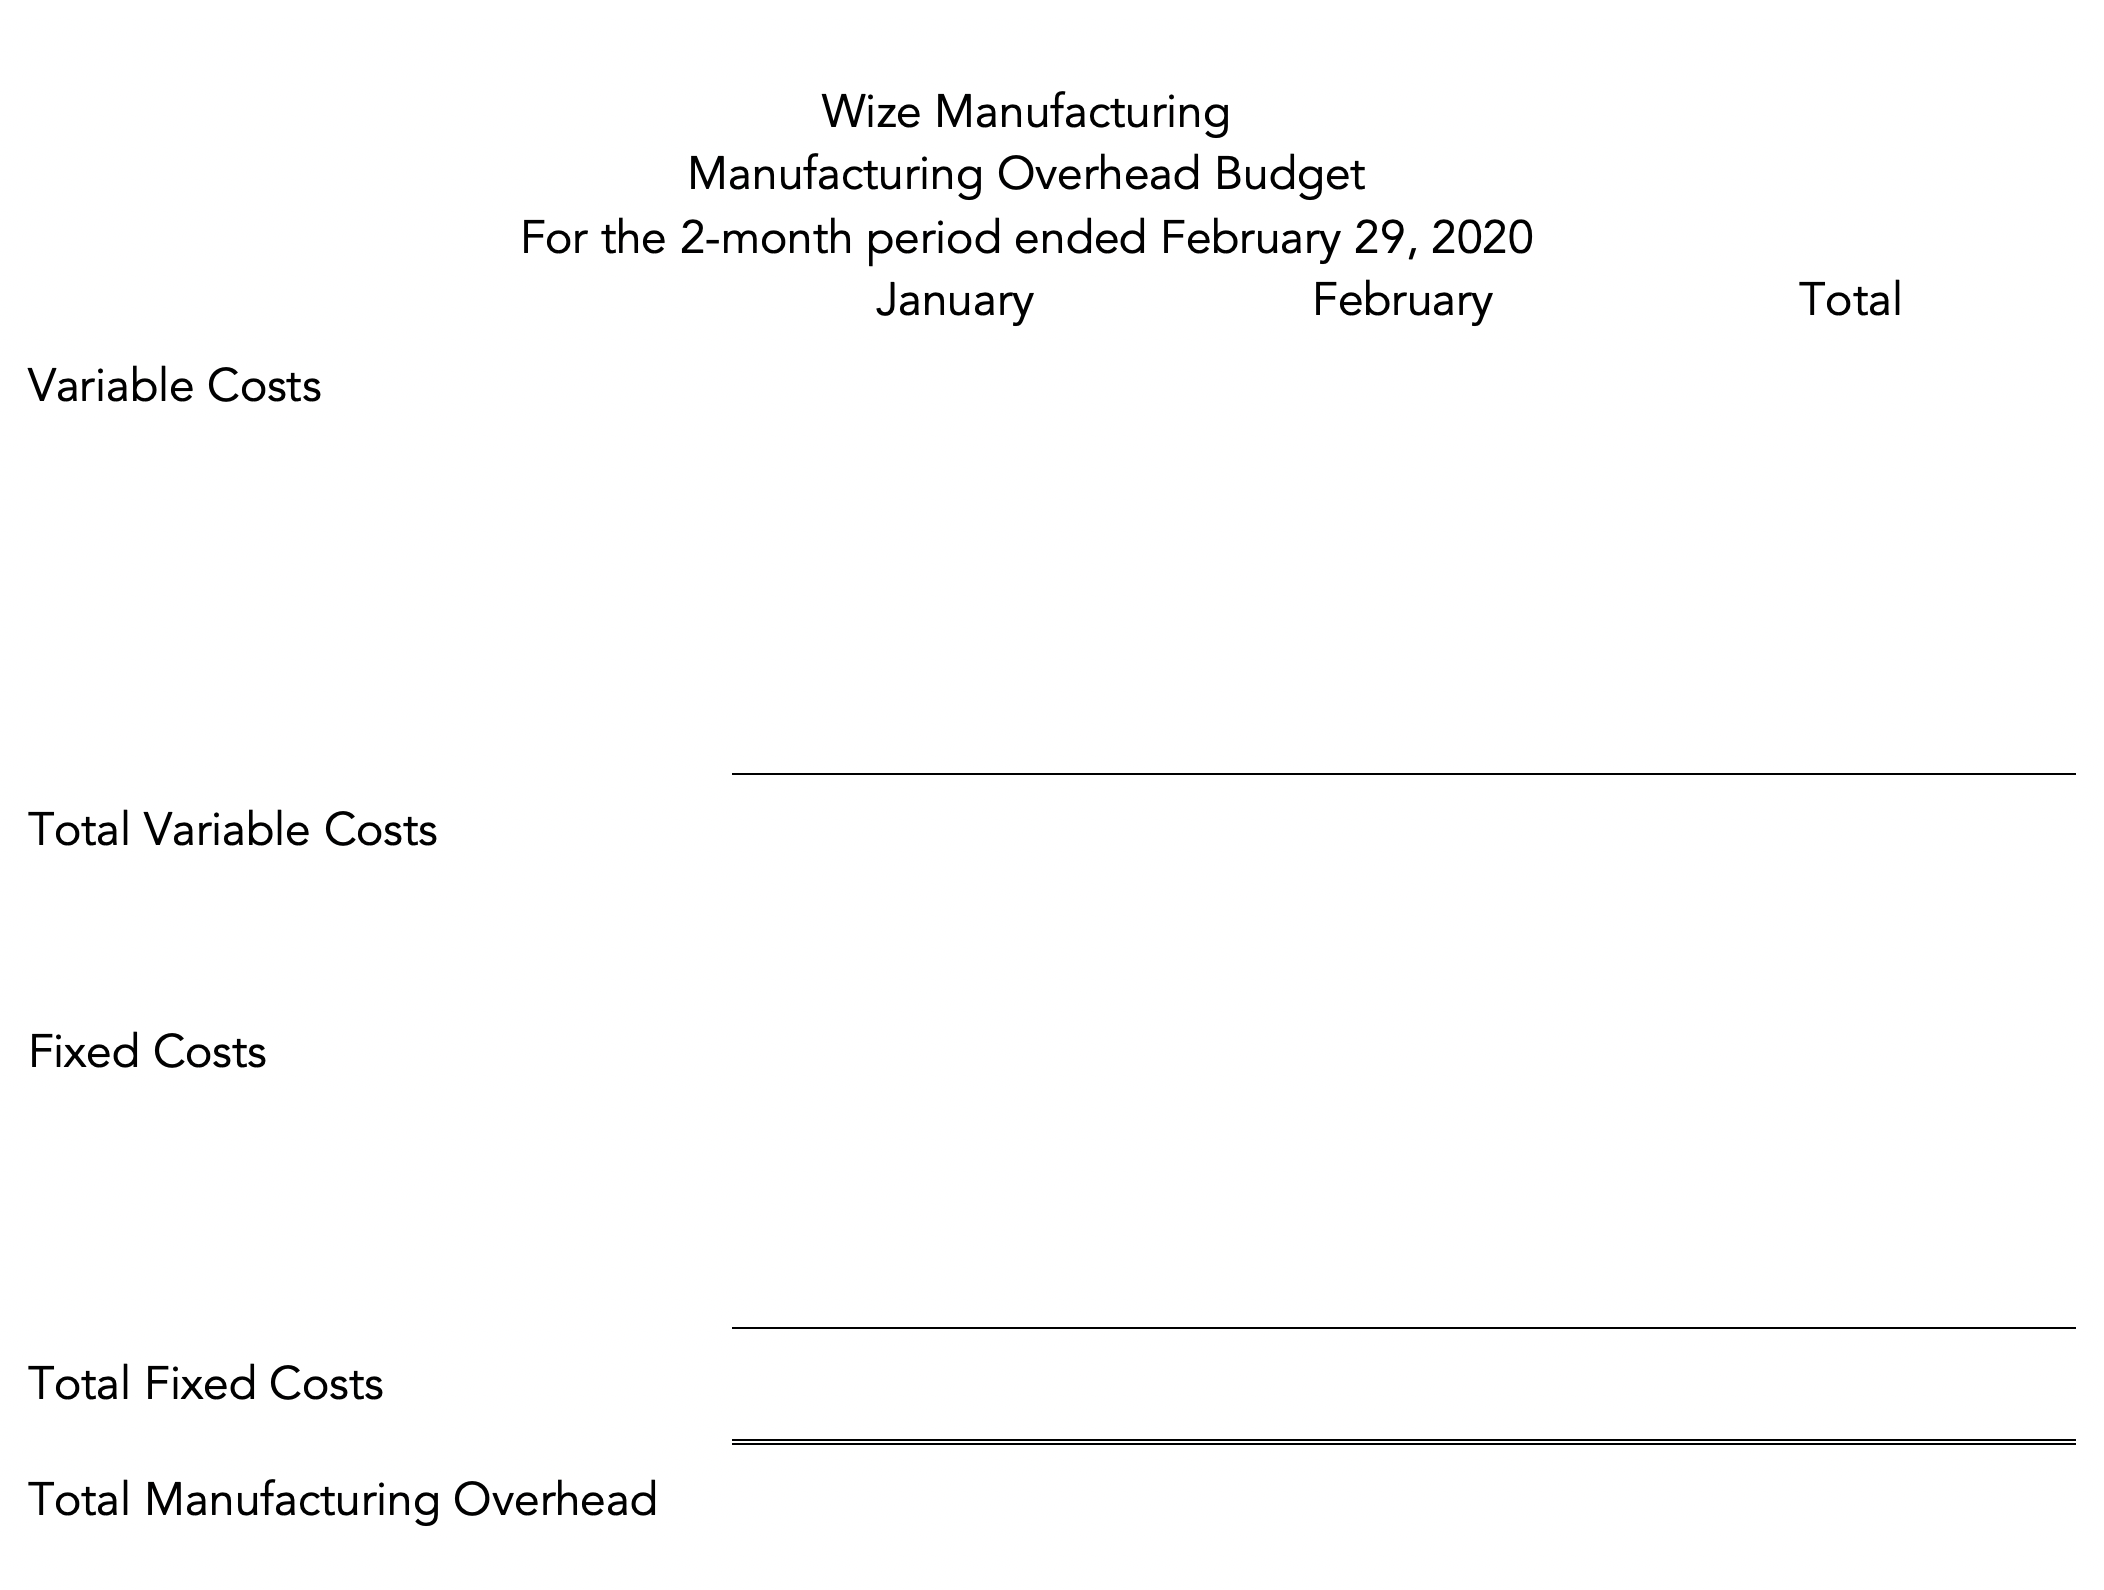
The manufacturing overhead budget shows how much the company expects to spend on manufacturing overhead during the budgeted periods. In this budget variable and fixed manufacturing overhead are budgeted separately and then added together at the end.
For Example
Wizedemy pays its workers $25 per hour and each unit of finished goods requires 1.5 hours of labour to be produced. In addition, the company estimates that variable manufacturing overhead will cost the following per hour: $2 for indirect materials, $3 for indirect labour and $0.70 for utilities. Depreciation on factory equipment is expected to be $10,000 per month and the supervisors salary is $8,000 per month.


Example: Direct Labour and Manufacturing Overhead Budget
The following information was collected from Wize Manufacturing on January 1st 2020:
Unit Sales
December 2019 (Actual): 1,000
January 2020 (Expected): 1,200
February 2020 (Expected): 1,400
March 2020 (Expected): 1,700
April 2020 (Expected): 1,600
The company’s selling price has been $50 per unit for quite some time, and it expects to increase this to $60 per unit starting February 2020. 40% of sales are made in cash, the rest is on credit. Credit sales are collected as follows: 60% in the month of sale, 35% the month following the sale, and 5% are uncollectible.
It takes 2kg of materials to produce one unit of finished goods, the company’s supplier charged $5 per kg in 2019 and has not informed the company that they will increase the price. All material purchases are on account, 20% of which are paid in the month of purchase and the rest paid for the month after. It takes 1.5 hours of labour to produce each unit and factory workers are paid $20 per hour. Manufacturing overhead consists of: $2 per unit of indirect materials, $3 per unit of indirect labour, $0.75 per unit for utilities, $120,000 per year in rent and $60,000 per year in depreciation on factory equipment. The company ends each month with 20% of next months unit sales and 40% of next month’s direct materials needed for production.
The company pays 5% commissions on sales and has a marketing budget of $2,000 per month. Other operating expenses total $6,000 per month (including $1,000 of depreciation on office equipment.)
The company plans to issue 5,000 new shares for $10 per share in February 2019 and It plans on purchasing a new piece of equipment for $60,000 in January; and it plans on declaring and paying a dividend of $10,000 in January.
The company ended 2019 with $16,000 in cash, $10,000 in net accounts receivable and $12,000 in accounts payable. Ending direct materials inventory was zero in 2019, and the company’s minimum cash balance is $15,000. Borrowings are made in multiples of $500 and the company’s line of credit carries a 12% annual interest rate. Borrowings are made at the beginning of the month and repayments are made the end of the month.
Prepare the Direct Labour and Manufacturing Overhead Budgets for the first 2 months of 2020
The Selling and Administrative Budget
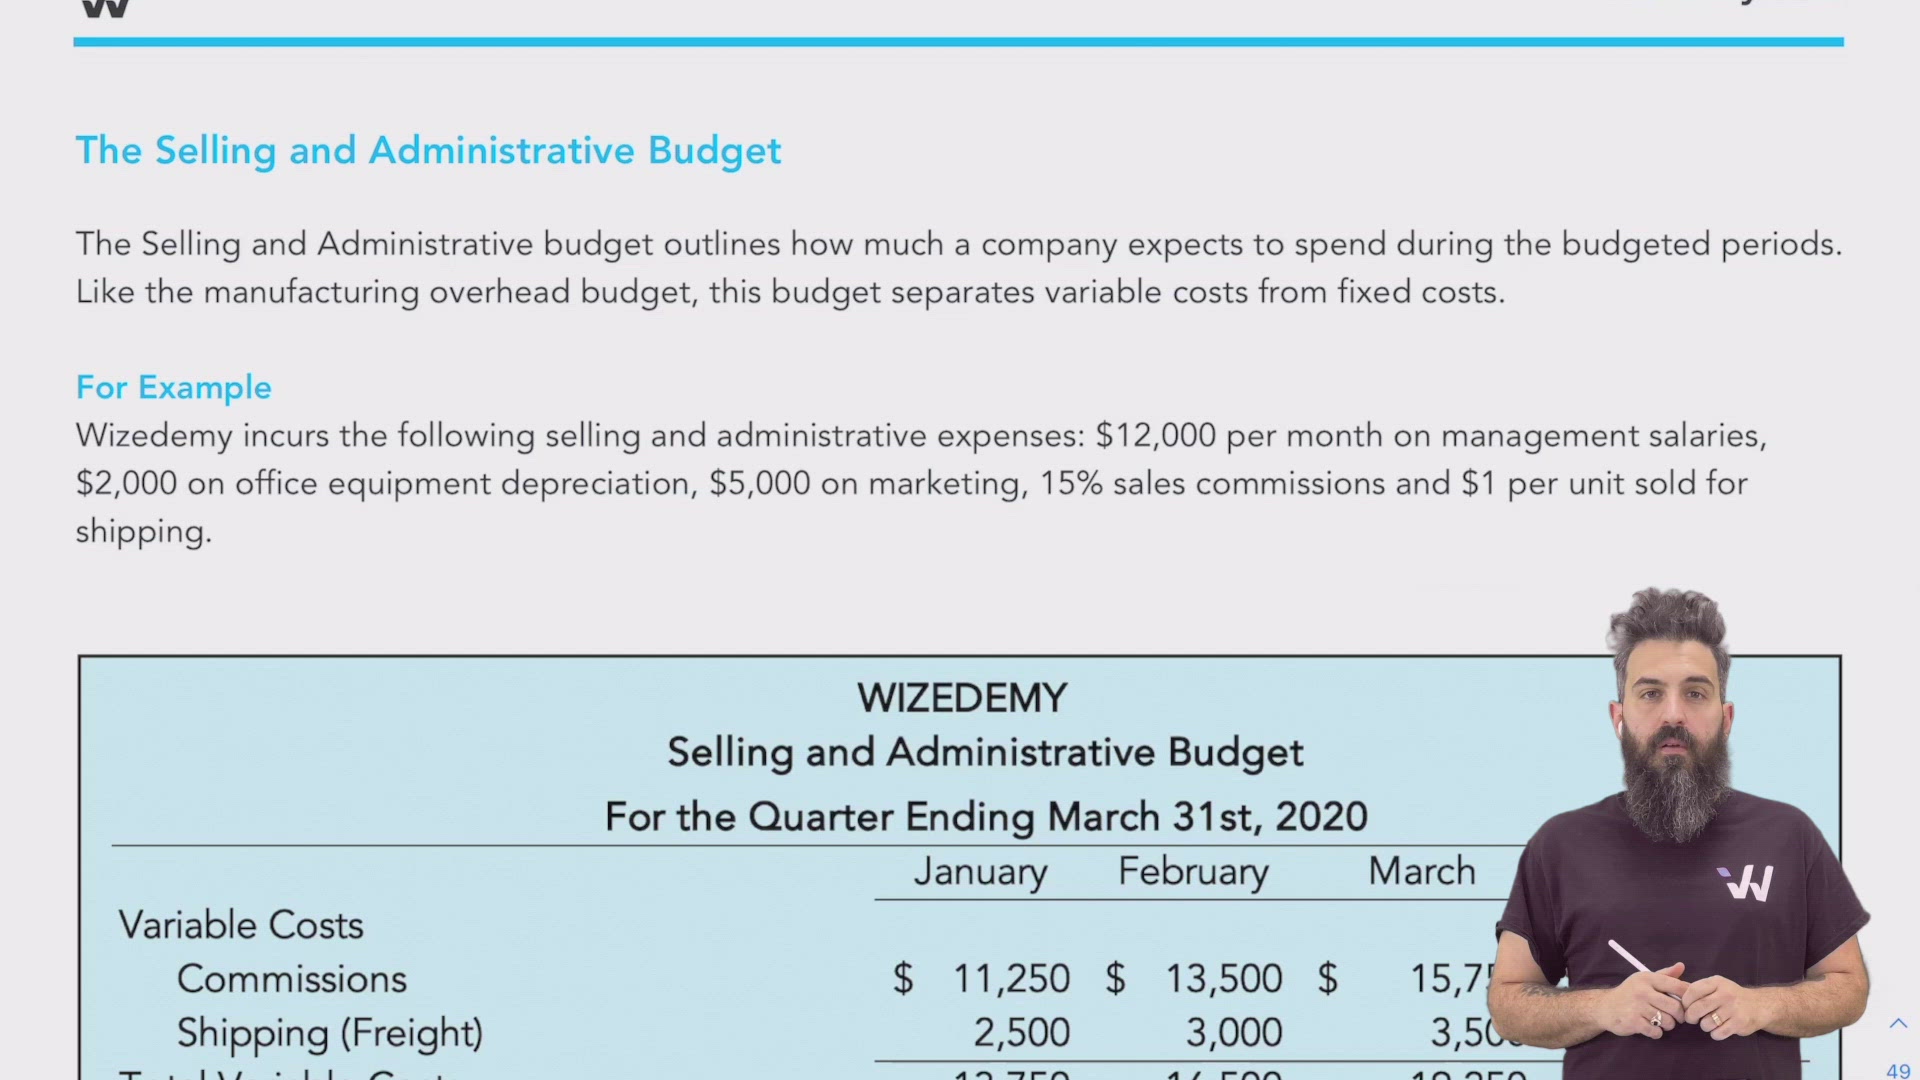
The Selling and Administrative budget outlines how much a company expects to spend during the budgeted periods. Like the manufacturing overhead budget, this budget separates variable costs from fixed costs.
For Example
Wizedemy incurs the following selling and administrative expenses: $12,000 per month on management salaries, $2,000 on office equipment depreciation, $5,000 on marketing, 15% sales commissions and $1 per unit sold for shipping.

Example: Selling and Administrative Budget
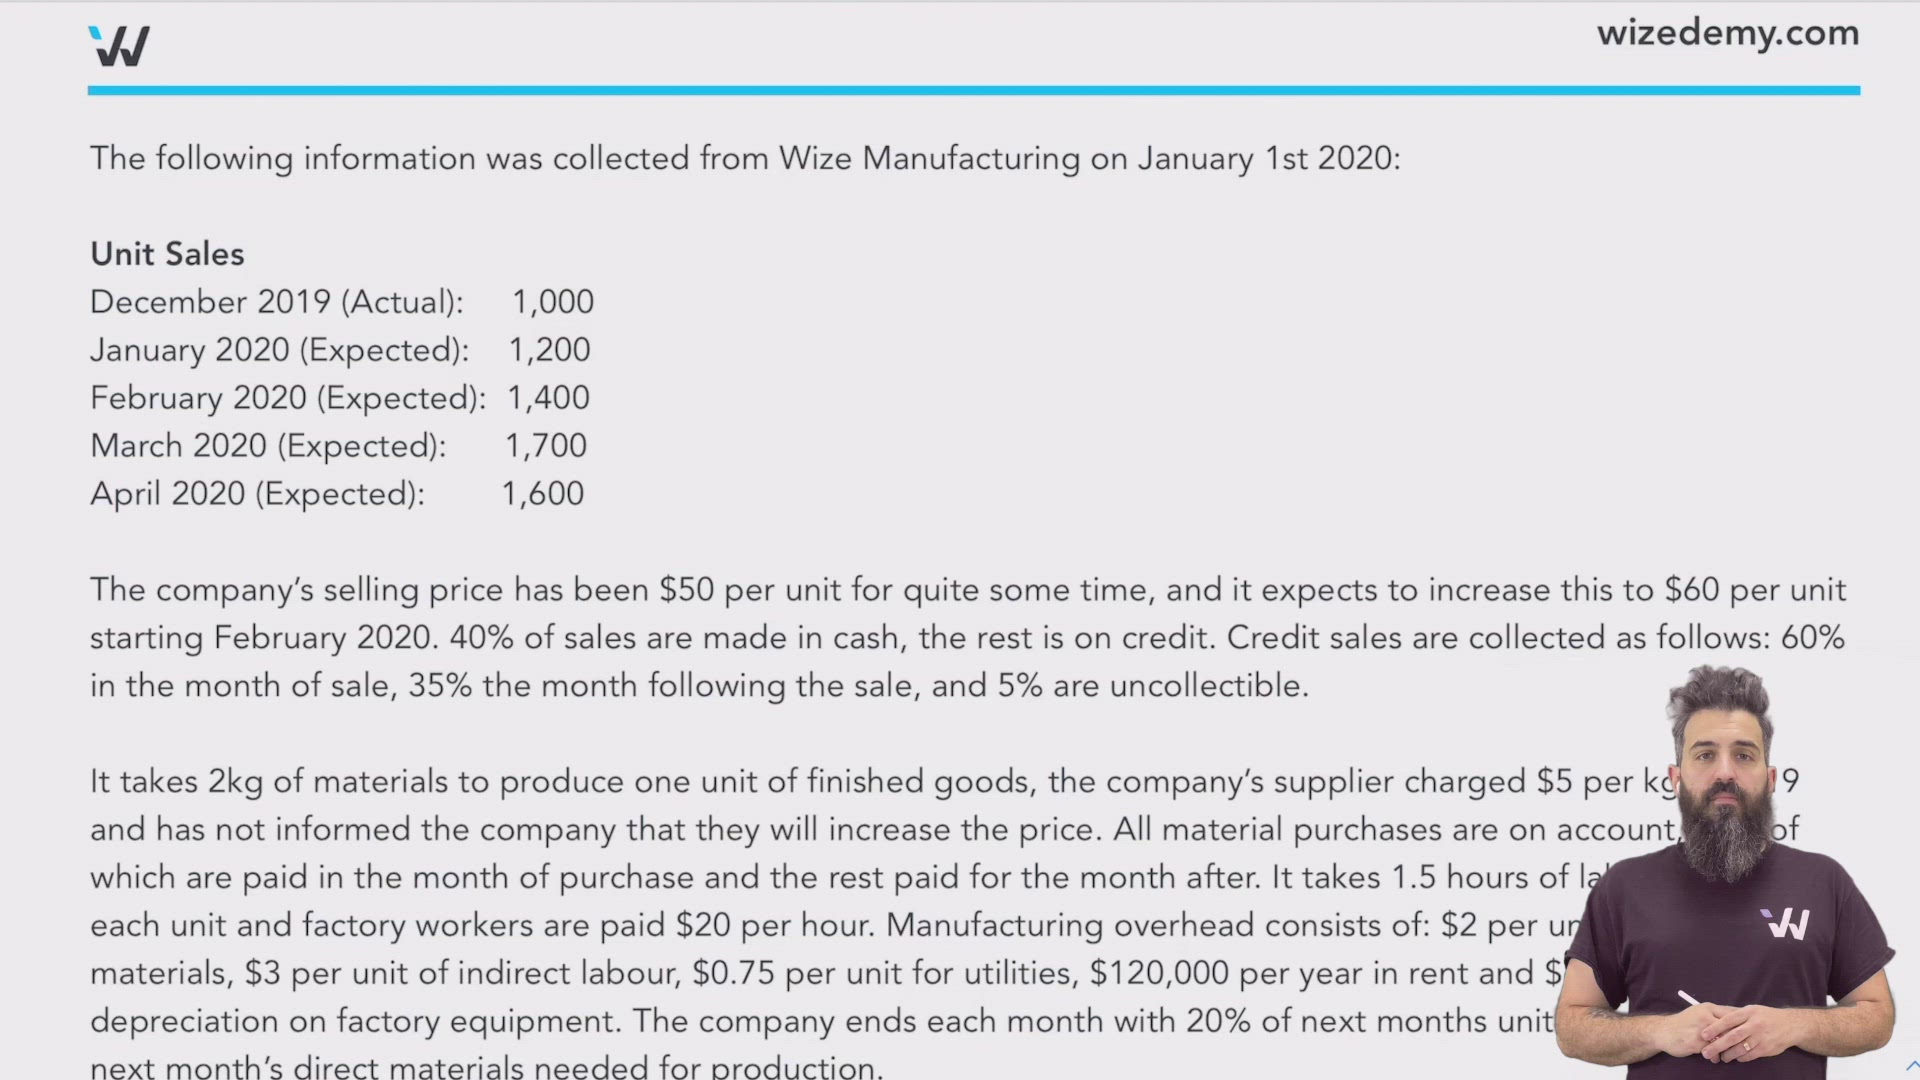
The following information was collected from Wize Manufacturing on January 1st 2020:
Unit Sales
December 2019 (Actual): 1,000
January 2020 (Expected): 1,200
February 2020 (Expected): 1,400
March 2020 (Expected): 1,700
April 2020 (Expected): 1,600
The company’s selling price has been $50 per unit for quite some time, and it expects to increase this to $60 per unit starting February 2020. 40% of sales are made in cash, the rest is on credit. Credit sales are collected as follows: 60% in the month of sale, 35% the month following the sale, and 5% are uncollectible.
It takes 2kg of materials to produce one unit of finished goods, the company’s supplier charged $5 per kg in 2019 and has not informed the company that they will increase the price. All material purchases are on account, 20% of which are paid in the month of purchase and the rest paid for the month after. It takes 1.5 hours of labour to produce each unit and factory workers are paid $20 per hour. Manufacturing overhead consists of: $2 per unit of indirect materials, $3 per unit of indirect labour, $0.75 per unit for utilities, $120,000 per year in rent and $60,000 per year in depreciation on factory equipment. The company ends each month with 20% of next months unit sales and 40% of next month’s direct materials needed for production.
The company pays 5% commissions on sales and has a marketing budget of $2,000 per month. Other operating expenses total $6,000 per month (including $1,000 of depreciation on office equipment.)
The company plans to issue 5,000 new shares for $10 per share in February 2019 and It plans on purchasing a new piece of equipment for $60,000 in January; and it plans on declaring and paying a dividend of $10,000 in January.
The company ended 2019 with $16,000 in cash, $10,000 in net accounts receivable and $12,000 in accounts payable. Ending direct materials inventory was zero in 2019, and the company’s minimum cash balance is $15,000. Borrowings are made in multiples of $500 and the company’s line of credit carries a 12% annual interest rate. Borrowings are made at the beginning of the month and repayments are made the end of the month.
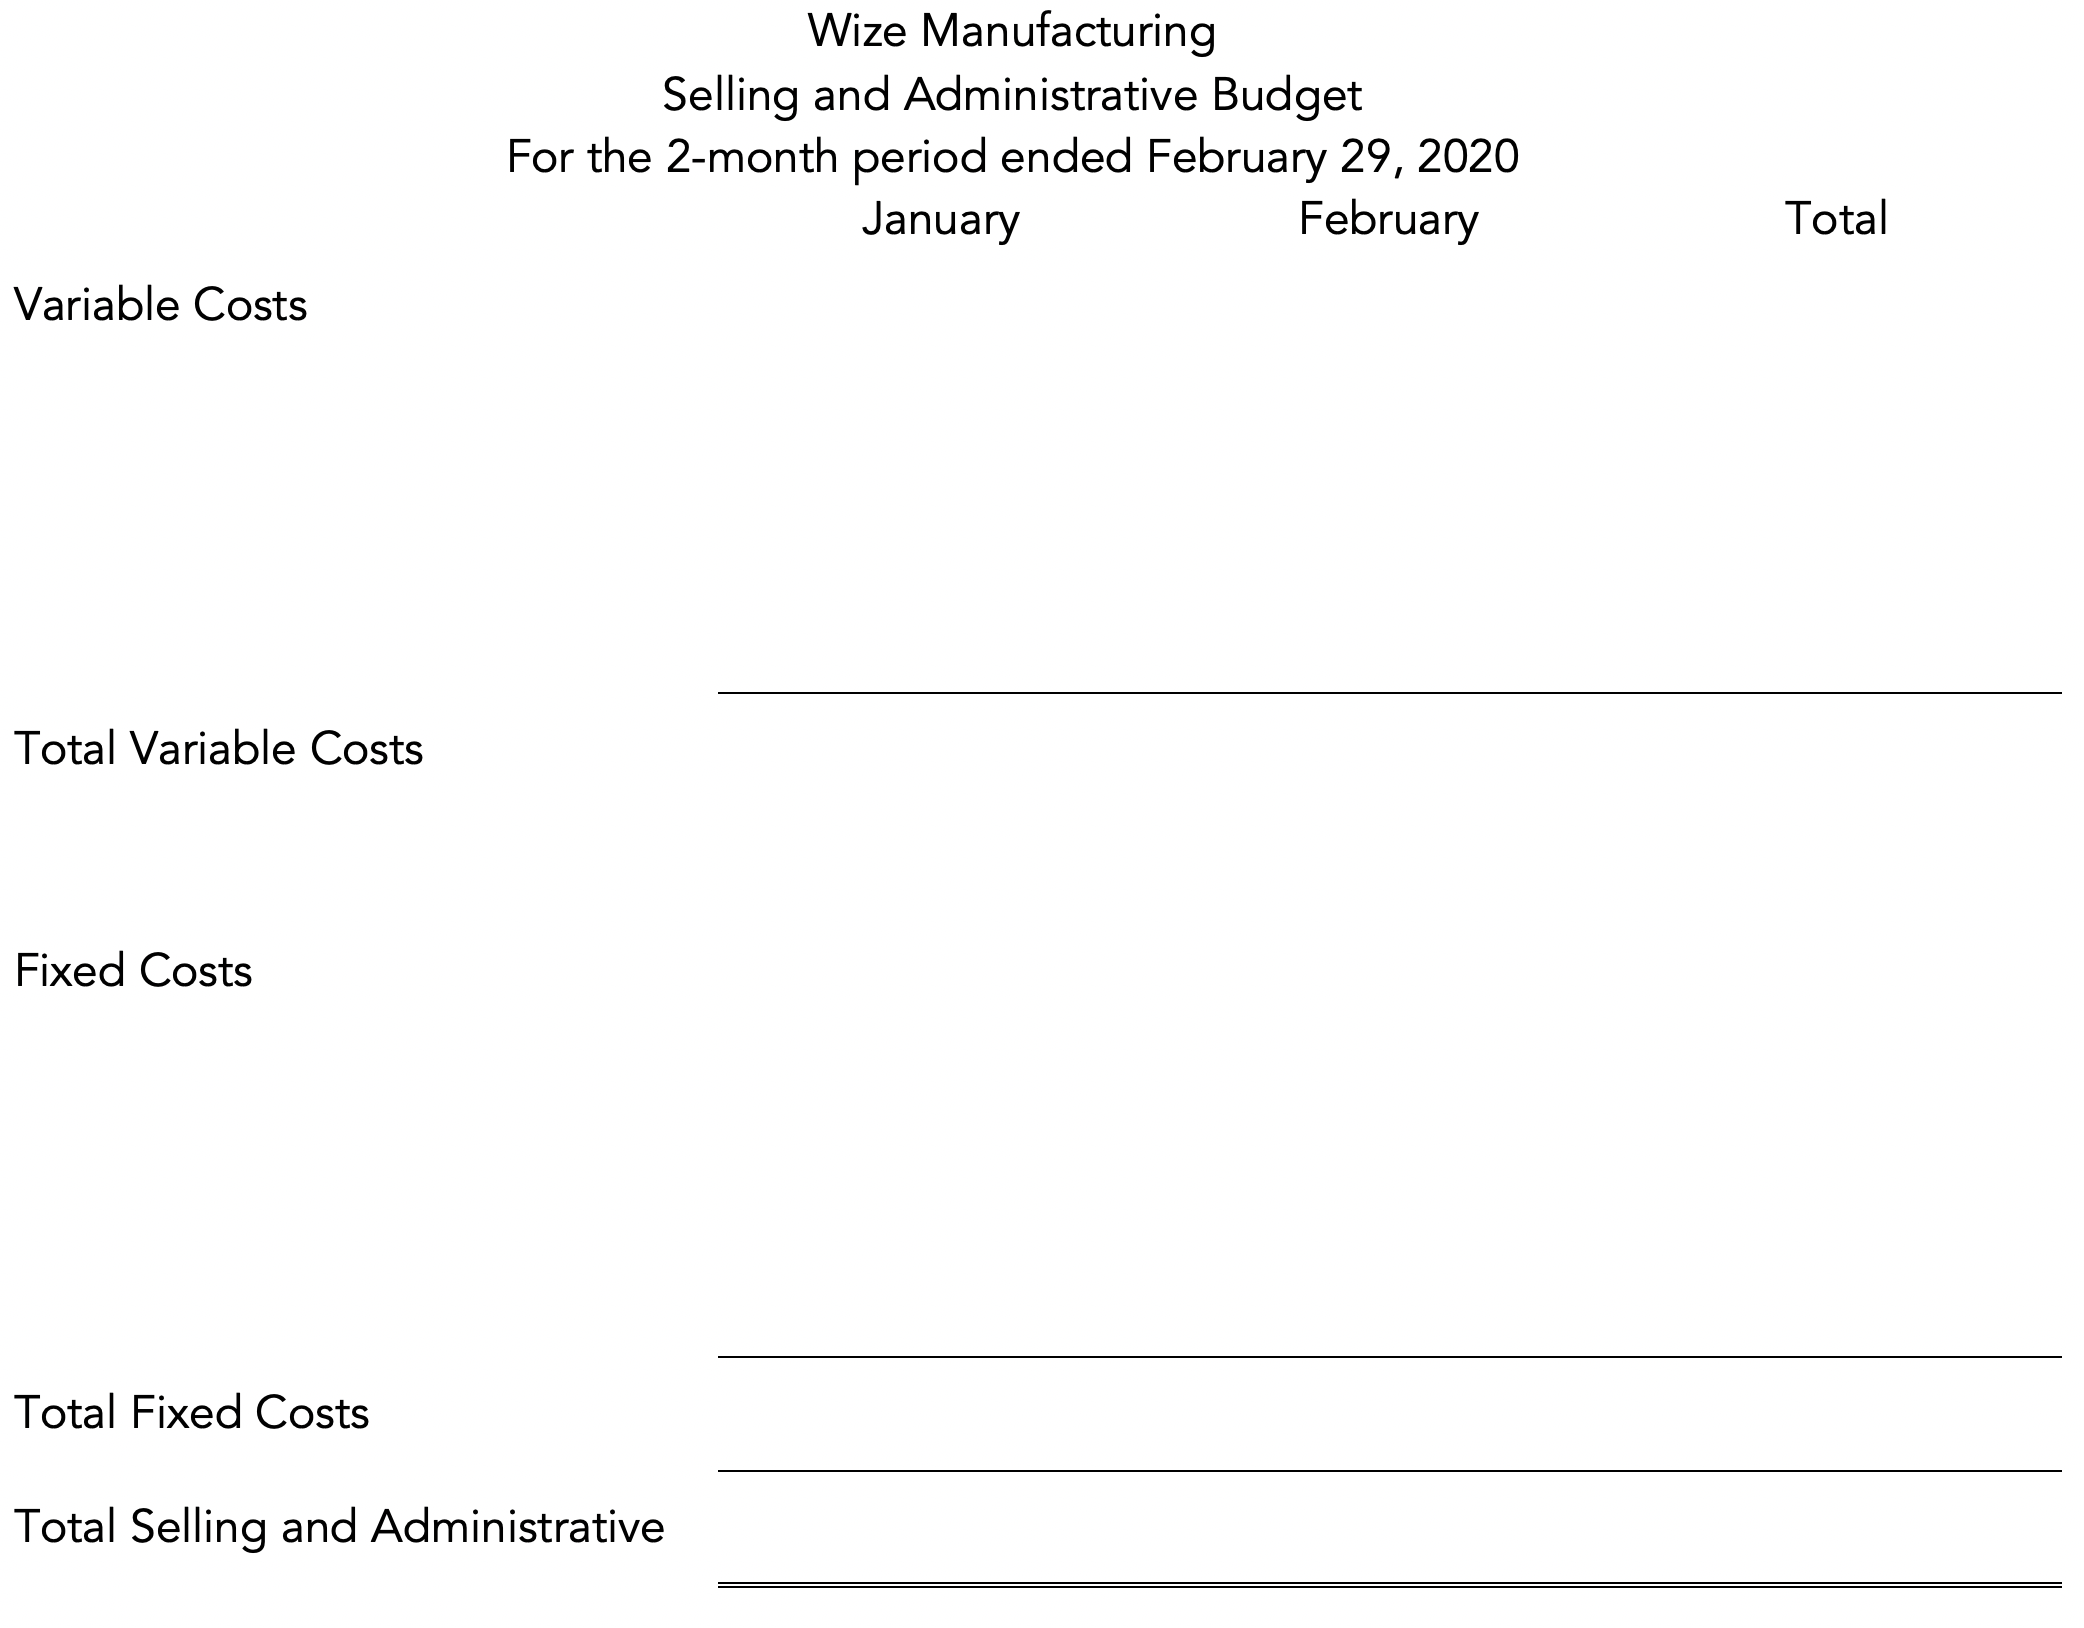
Prepare the Selling and Administrative Budget for the first 2 months of 2020
The Cash Budget
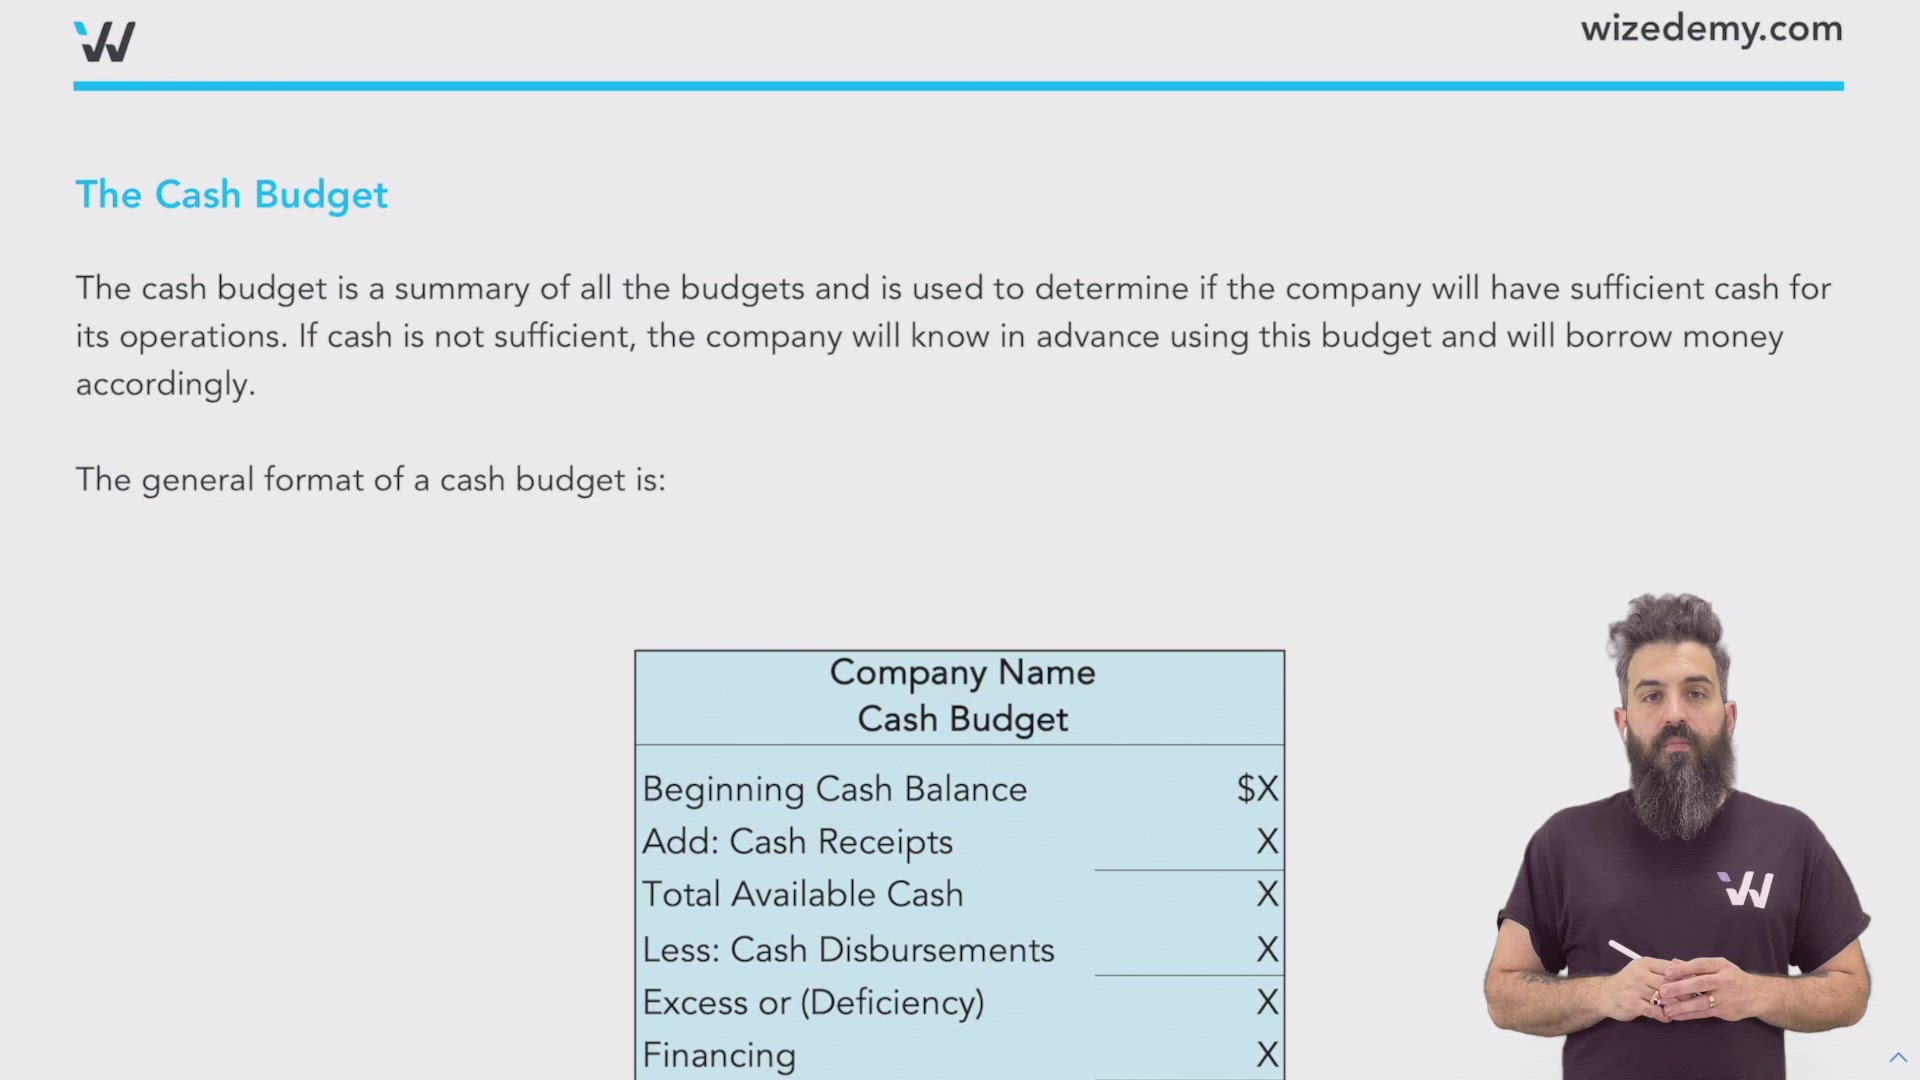
The cash budget is a summary of all the budgets and is used to determine if the company will have sufficient cash for its operations. If cash is not sufficient, the company will know in advance using this budget and will borrow money accordingly.
The general format of a cash budget is:

Cash Receipts
This section includes a list of all sources of cash (except borrowings). Can include: collections from customers, proceeds from sale of assets, proceeds from issuance of shares, etc.
Cash Disbursements
This section includes a list of all expenditures of cash. Can include: payments for inventory purchases, direct labour, manufacturing overhead, selling and administrative expenses, purchases of assets, payments of dividends, etc.
Depreciation
When preparing the cash budget, you must always exclude depreciation because it is a non-cash expense. This includes both depreciation found in manufacturing overhead and in selling and administrative expenses.
Financing
Minimum Cash Balance and Borrowings
Every company has a minimum amount of cash that they must maintain each period. If cash is expected to fall below the minimum, the company will borrow the amount needed at the beginning of the period it expects to have the cash deficiency.
Repayments
If excess cash is greater than the minimum cash balance, the excess should be used to repay any existing borrowings and related interest. Repayments are made at the end of the period that the company expects to have the cash excess.
Interest
When some or all of the previous borrowings are repaid, the interest accrued is also repaid. It is important to remember that borrowings are made at the beginning of a period and repayments are made at the end of a period because it will affect the calculations of interest. For example if you borrow $5,000 in January and repay it in February, the interest is accrued for two months, not one. This is because the borrowing was done at the beginning of January and the repayment at the end of February.
For Example
Wizedemy has a minimum cash balance of $10,000. On December 31st, 2019 it had $12,500 in cash and the company can borrow at a rate of 12% per year.
