
Beta
Market risk (systematic risk) is the risk associated with the overall market and is measured using beta (). The beta of a stock simply measures the change of the stock relative to the change in the overall market. For example, if a stock has a beta of 2, it will move by 2% whenever the market moves by 1%.
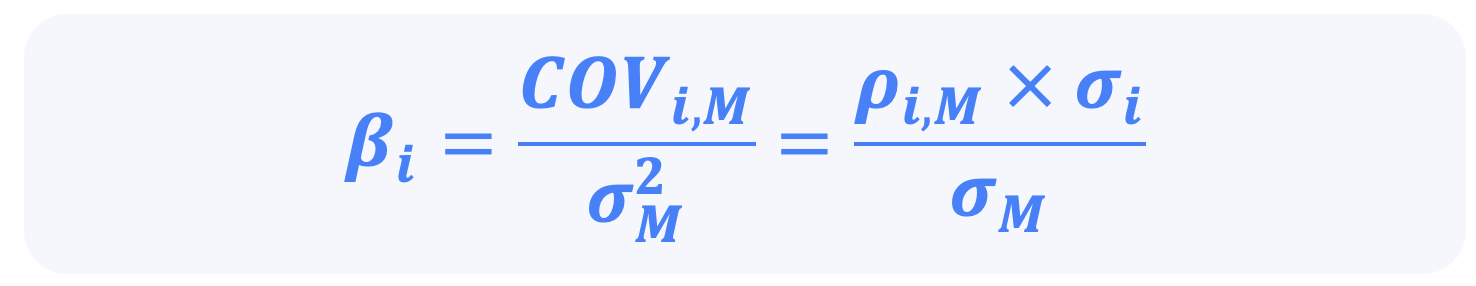
Important Betas to Remember
- The market always has a beta of 1
- Risk-free assets always have a beta of 0
Portfolio Beta
A portfolio beta is simply the weighted average of the stock beta's that make up the portfolio. For example, if a portfolio was 40% invested in Stock A with a beta of 1.2 and 60% invested in Stock B with a beta of 0.7 the portfolio beta would be 0.4(1.2) + 0.6(0.7) = 0.9
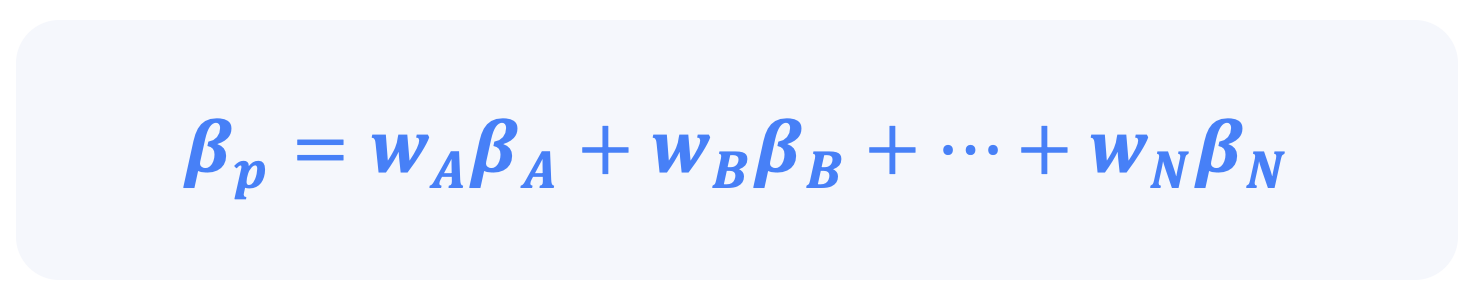
Example: Market Risk and Beta
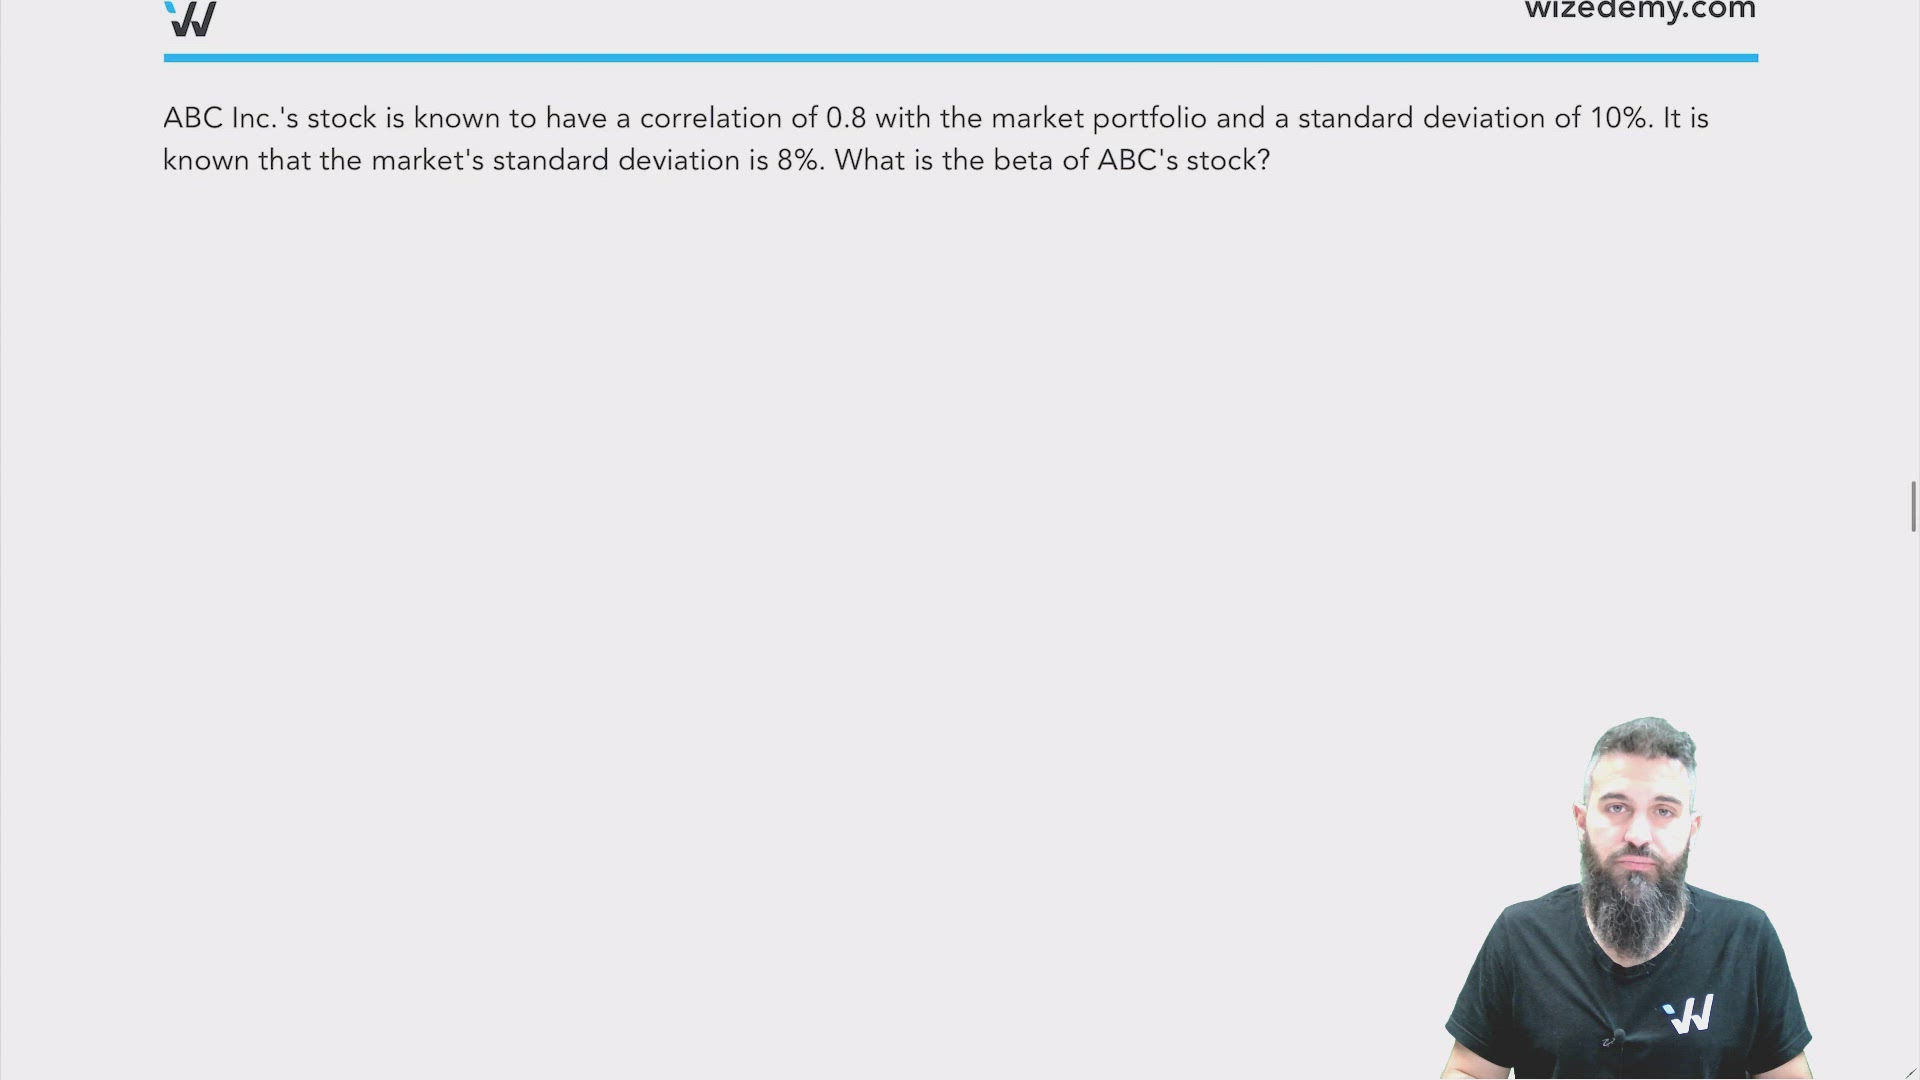
ABC Inc.'s stock is known to have a correlation of 0.8 with the market portfolio and a standard deviation of 10%. It is known that the market's standard deviation is 8%. What is the beta of ABC's stock?
Example: Market Risk and Beta
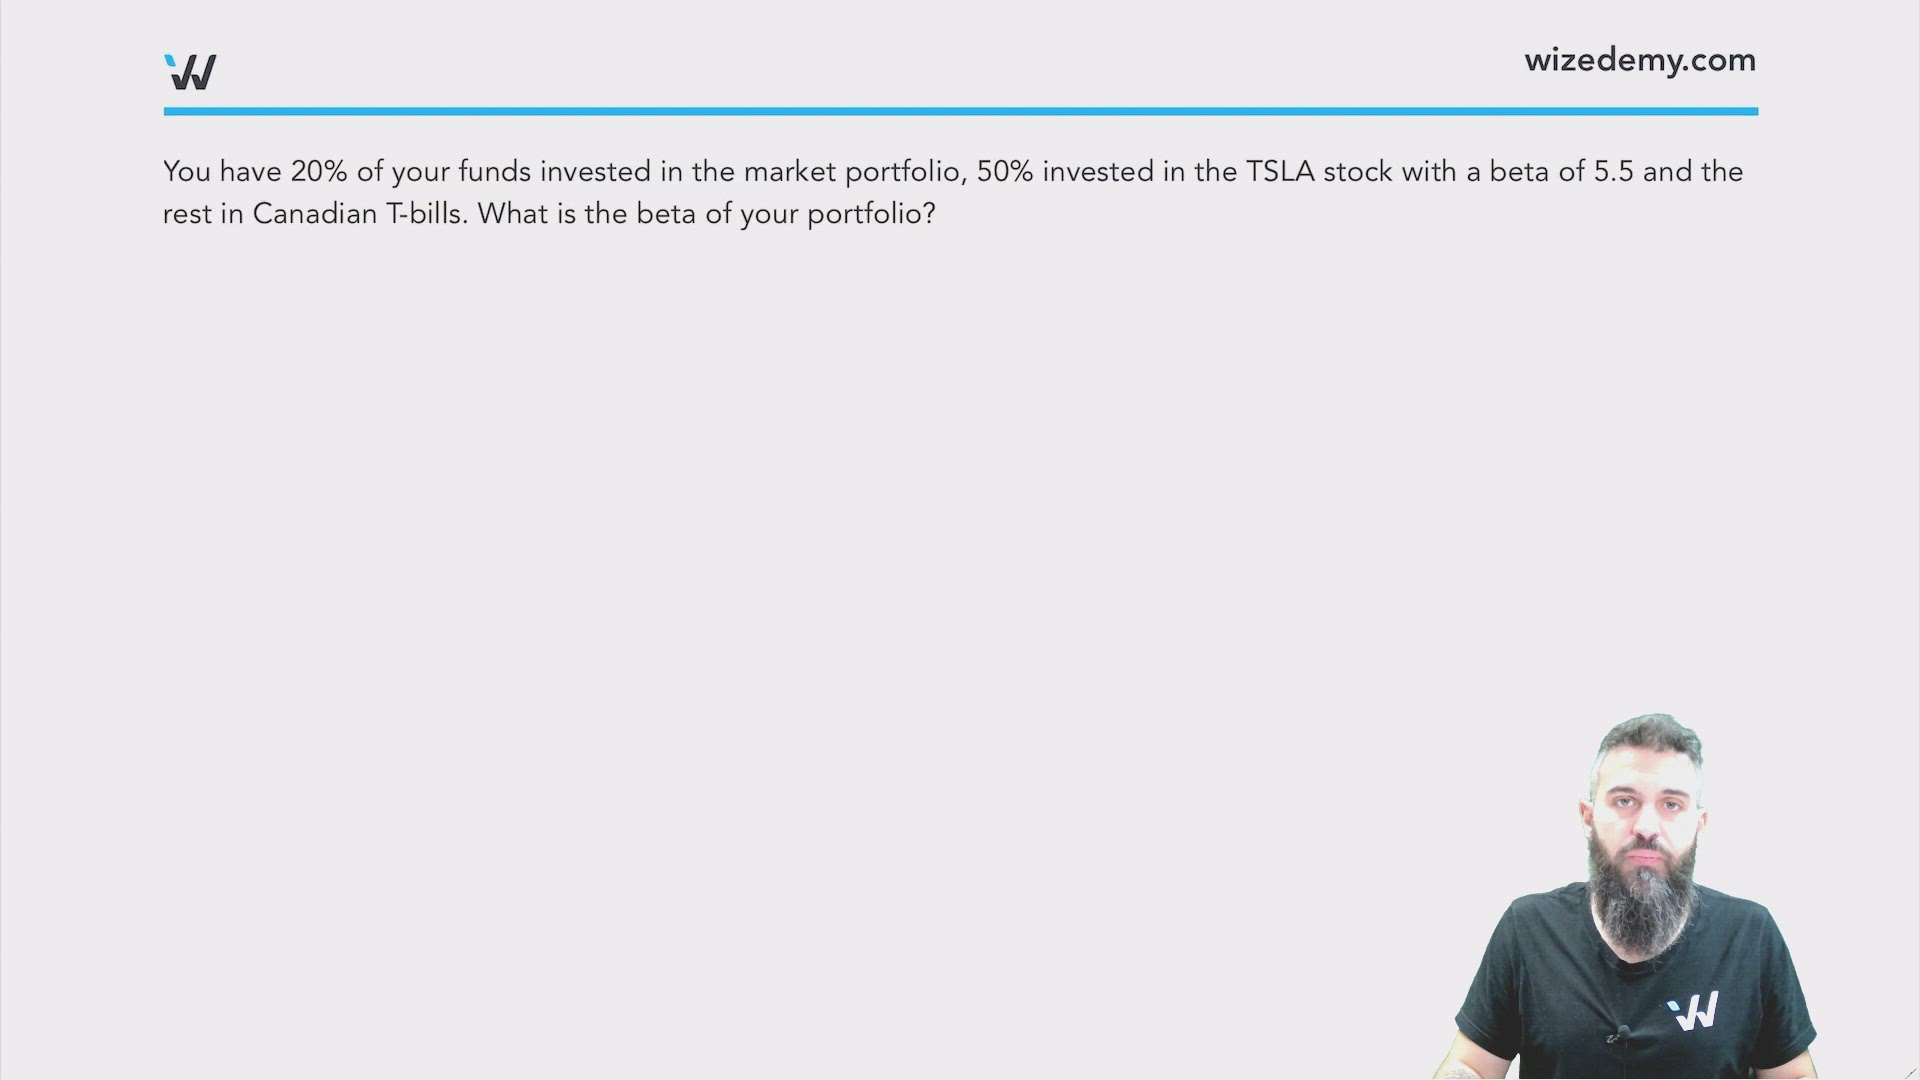
You have 20% of your funds invested in the market portfolio, 50% invested in the TSLA stock with a beta of 5.5, and the rest in Canadian T-bills. What is the beta of your portfolio?