Put-Call Parity
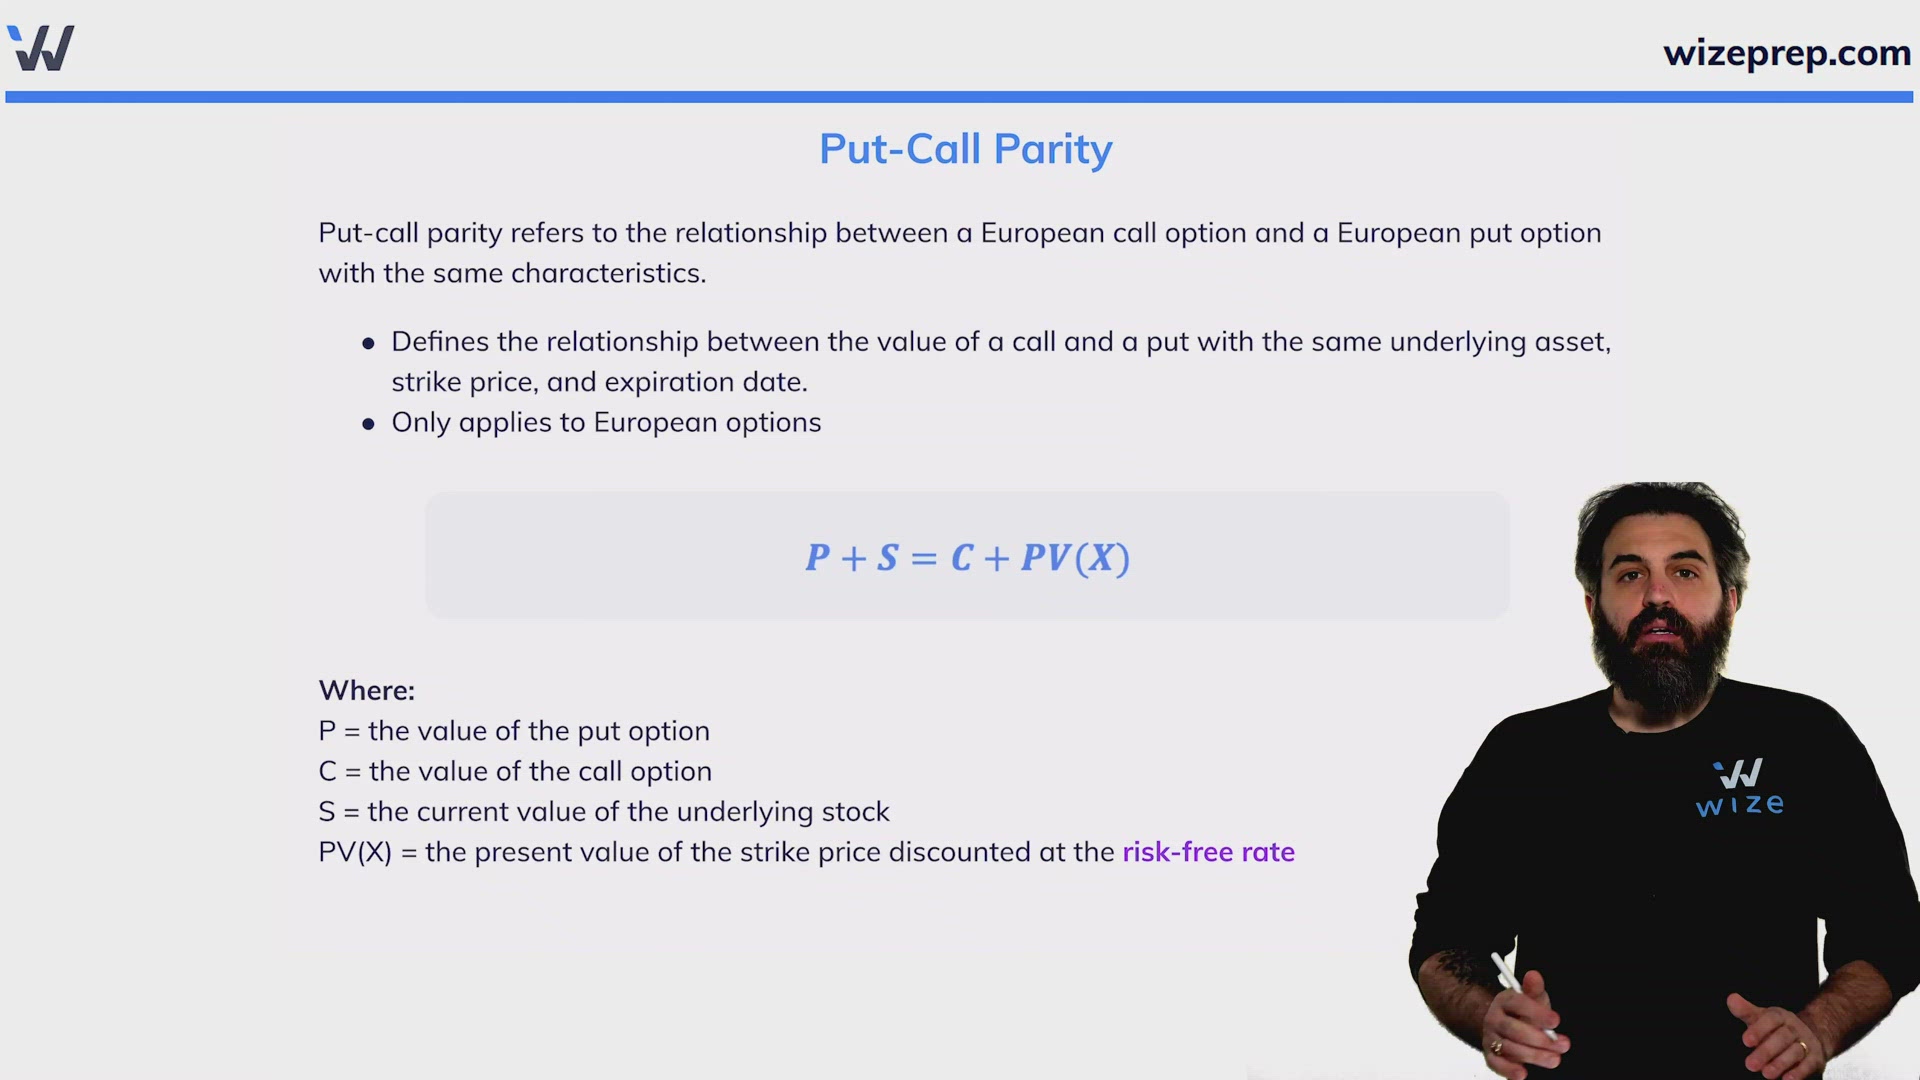
Put-call parity refers to the relationship between a European call option and a European put option with the same characteristics.
- Defines the relationship between the value of a call and a put with the same underlying asset, strike price, and expiration date.
- Only applies to European options
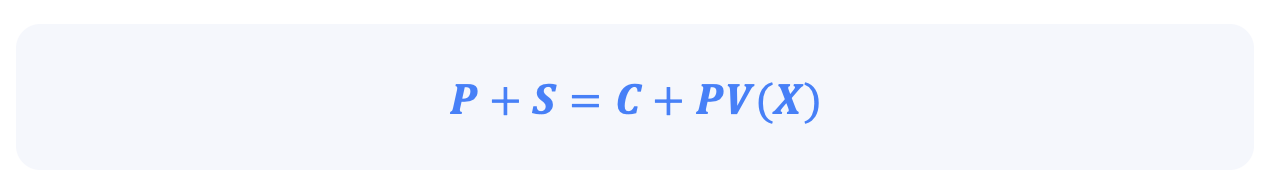
Where:
P = the value of the put option
C = the value of the call option
S = the current value of the underlying stock
PV(X) = the present value of the strike price discounted at the risk-free rate
Example: Put-Call Parity
Shares of ABC Inc are selling for $30, and a one-year European call option with a strike price of $40 is selling for $0.60. The risk-free rate is 7%, find the value of a one-year European put option with the same strike price.