Disposal of Assets
Assets are disposed of for a variety of reasons and in different ways. An asset can be sold, scrapped, destroyed or stolen, and while these events are very different in real life, they are fairly similar from an accounting stand point.
Before recording disposal:
- Record depreciation up to last day asset was used
Recording the disposal:
- Credit the asset at cost
- Debit all accumulated depreciation on the asset
- Debit proceeds from sale and/or expenses related to the sale
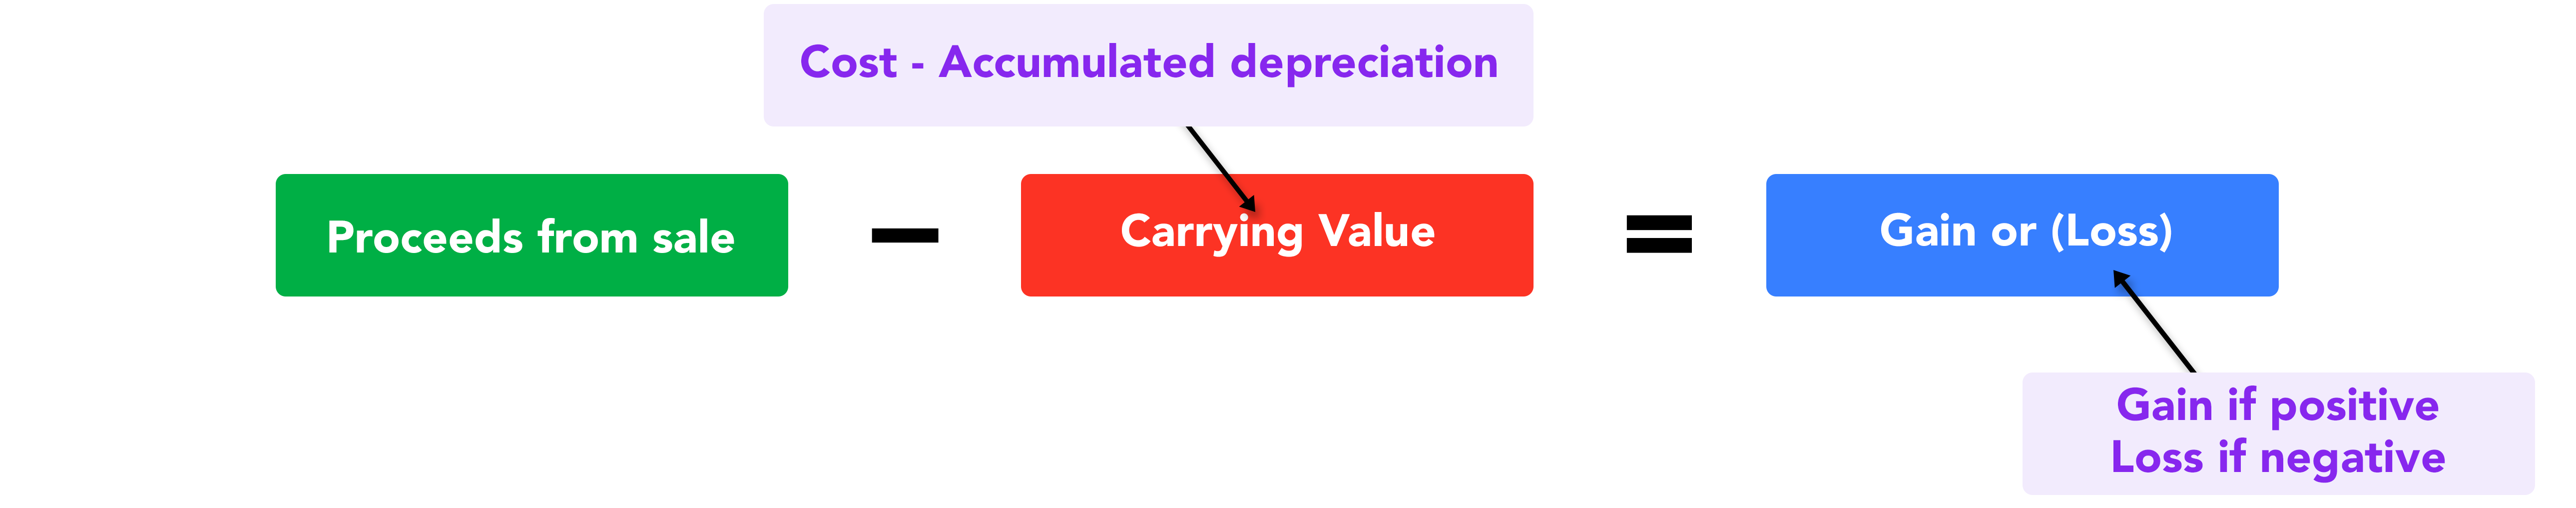
- Debit loss on sale or Credit gain on sale.
Example: Disposal of Assets
ABC Inc. has received an offer to sell one of its buildings on July 1st, 2020 for $4,300,000 in cash. The building was purchased for $1,500,000 20 years ago, and at the the time had a residual value of $200,000 and an estimated useful life of 40 years. Buildings are depreciated using the straight-line method.
Prepare the necessary journal entries on the date of the sale.
Journal entry to record depreciation
Journal entry to record the sale of the building